- Last week went Choppy, Choppy, Choppy, Choppy, Bleeding, and the average stock won it: the equal-weight S&P rose about 0.8% while the S&P proxy slipped about 0.6% and the Nasdaq proxy about 2.0% after Intel's 28.5% Friday collapse.
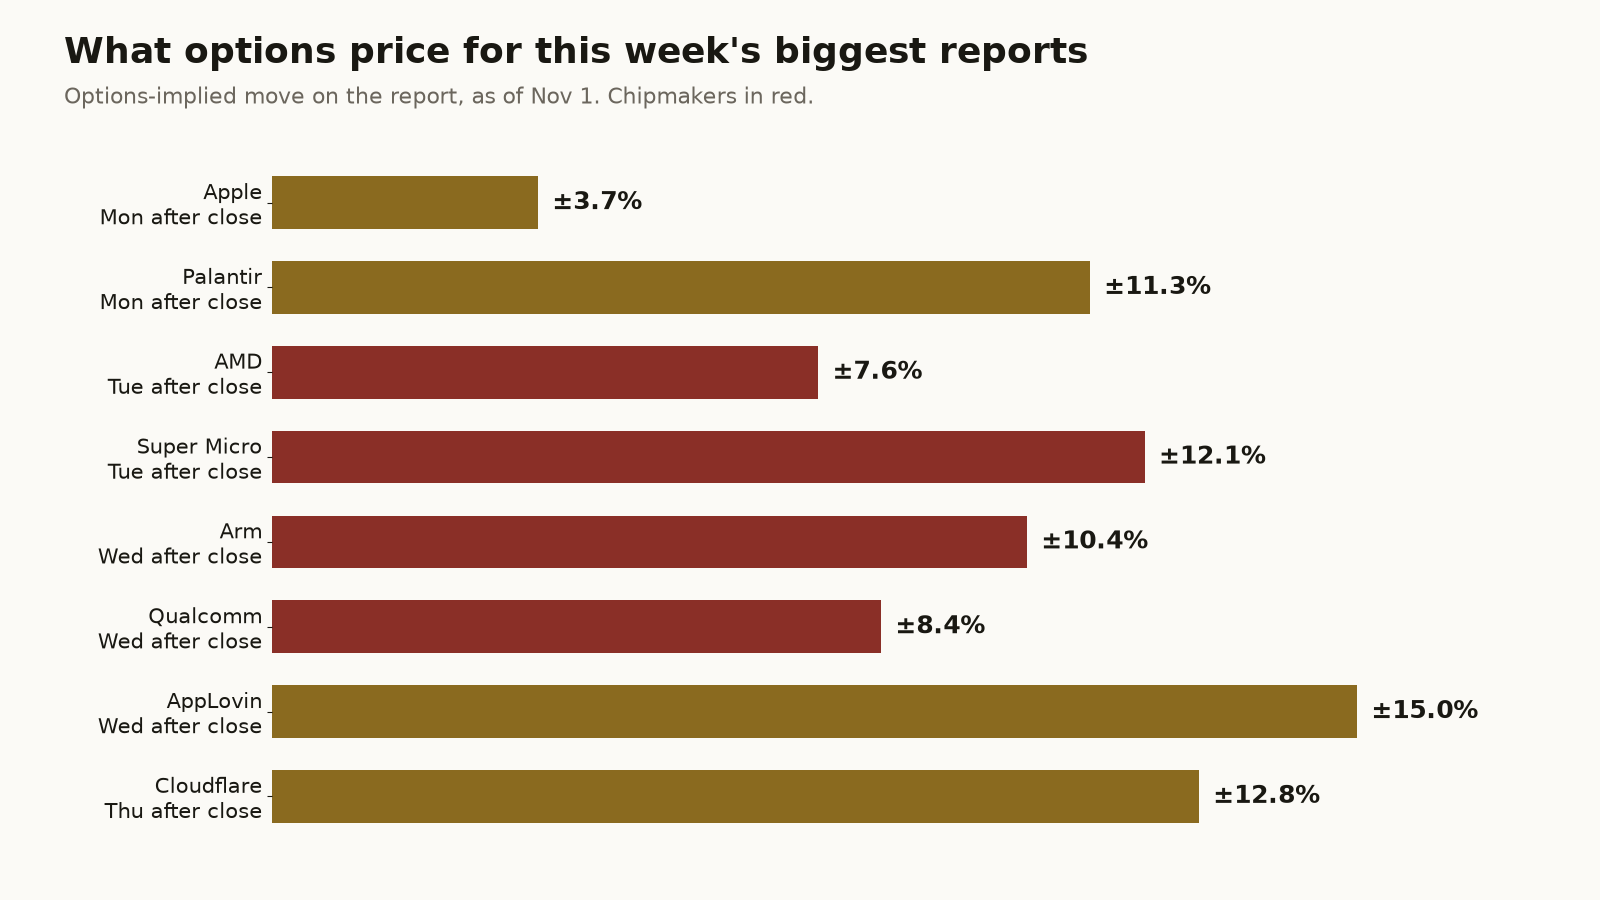
- The week's question is whether Intel's crash was Intel's problem or the start of a chip selloff. Tuesday answers it, with AMD after the close (implied move ±7.6%), then Arm and Qualcomm Wednesday after the close.
- Monday has the manufacturing PMI at 9:45 AM ET (prior 55.9) and ISM manufacturing at 10:00 AM ET (prior 54.5), Marriott before the open, and Apple and Palantir after the close.
Key numbers
The week ahead
- 9:45 AM Manufacturing PMI (prior 55.9)
- 10:00 AM ISM manufacturing (prior 54.5)
- 10:00 AM Construction spending (prior +0.9%)
- MAR BMO · IDXX BMO · AAPL AMC · PLTR AMC · VRTX AMC · WMB AMC · ON AMC
- US midterm elections
- 10:00 AM JOLTS job openings (prior 7.1M)
- 10:00 AM Factory orders (prior +0.1%)
- SHOP BMO · PFE BMO · ETN BMO · MPC BMO · AMD AMC · AMGN AMC · ANET AMC · BKNG AMC · SMCI AMC
- 8:15 AM ADP employment (prior +90K)
- 8:30 AM Trade balance (prior −$105.6B)
- 9:45 AM Services PMI (prior 58.8)
- 10:00 AM ISM services (prior 54.9)
- MCD BMO · UBER BMO · NVO BMO · CVS BMO · DDOG BMO · ARM AMC · QCOM AMC · APP AMC · DASH AMC · MELI AMC
- 8:30 AM Weekly jobless claims
- COP BMO · SONY BMO · PH BMO · CI BMO · NET AMC · ABNB AMC · EOG AMC · MNST AMC · LITE AMC
- 8:30 AM October jobs report (prior +29K, unemployment 4.2%)
- 8:30 AM Average hourly earnings (prior +0.1% m/m, +3.0% y/y)
- 10:00 AM Consumer sentiment, preliminary (prior 46.3)
- 3:00 PM Consumer credit (prior +$8.3B)
- ENB BMO · MRNA BMO · HUM BMO · VST BMO
Last week spent four days Choppy and then turned Bleeding on Friday, when Intel fell about 28.5% on a weak outlook and dragged the chip ETF down about 6.9% in a day. The equal-weight S&P still finished the week up about 0.8% while the S&P proxy lost about 0.6%, so most stocks held up while the biggest ones did not. That leaves one question for this week: was Friday Intel's problem, or the first crack in the chip trade?
The week's question
Tuesday answers it. AMD reports after the close on midterm election night, with options pricing a move of about 7.6%, and Super Micro reports the same evening, priced for about 12.1%. Arm and Qualcomm follow Wednesday after the close, priced for about 10.5% and 8.4%. If AMD's outlook holds up, Friday reads as one company's stumble and the chip ETF has a case to win back part of its 6.9% drop. If AMD guides lower too, Intel's outlook starts to look like an industry signal, and Wednesday's reports land on a group already under pressure. Apple and Palantir set the tone first, Monday after the close, priced for about 3.7% and 11.3%.
Stories in play
The AI spending boom is cooling going in: the chip ETF fell about 6.9% Friday, and AMD, Super Micro, Arista, Arm and Qualcomm all report by Wednesday night. Oil keeps climbing meets a weekend of tanker headlines from the Strait of Hormuz, though crude fell about 0.4% last week; ConocoPhillips reports Thursday before the open and EOG Resources after the close. The average stock catching up gets its test from the labor data, with job openings Tuesday, ADP Wednesday and the October jobs report Friday at 8:30 AM ET, after September's payrolls rose only 29,000.
What X is saying
The weekend was about Iran again. Iran's state media said two oil tankers hit mines in the Strait of Hormuz on Sunday, after a tanker fire there on Saturday, and Iran's security chief vowed to keep the strait shut until Tehran's demands are met. Posts citing Axios said Netanyahu is pressing Trump to resume strikes on Iran right after Tuesday's midterms, while Trump wants more time for diplomacy, and wires reported Trump saying Washington is in no hurry to strike a deal and declining to say whether the US would return to war after the election. Posts also say US business investment in computers and software hit a record in the third quarter. These are claims from posts, not confirmed facts, except where Iran's state media is the source.
Desk stance for Monday
The desk goes into Monday Rattled. Friday's chip selloff hasn't been tested yet, and the weekend's Hormuz and strike headlines give crude a reason to open firm. ISM manufacturing at 10:00 AM ET is the only major release, so the open will trade chips and oil. A steady open with chips holding Friday's lows would ease the tape toward Choppy ahead of Apple and Palantir. Another leg down in chips, or a jump in crude on new strike talk, keeps it Rattled and could turn it Bleeding again.
- CoolingThe AI spending boomThe chip ETF fell 6.92% Friday on Intel's collapse, and AMD, Super Micro, Arm and Qualcomm report Tuesday and Wednesday after the close, priced for moves of 7.6% to 12.1%.
- SteadyOil keeps climbingCrude slipped 0.41% last week, but Iran's state media reported two tankers hitting mines in Hormuz on Sunday, and posts say strikes could resume after Tuesday's midterms.
- SteadyThe average stock catching upThe equal-weight S&P rose 0.82% last week against the S&P proxy's 0.56% drop; Friday's October jobs report (prior +29K) is its next test.
SOURCES ›
- Economic calendar, pulled Nov 1 5:07 PM ET, Nov 2–6 releases with priors (forecasts not listed): Manufacturing PMI 55.9, ISM manufacturing 54.5, construction spending +0.9%, JOLTS 7.1M, factory orders +0.1%, ADP +90,000, trade balance −$105.6B, services PMI 58.8, ISM services 54.9, weekly jobless claims, October employment report (prior +29,000, unemployment 4.2%, average hourly earnings +0.1% m/m and +3.0% y/y), consumer sentiment preliminary 46.3, consumer credit +$8.3B
- Release times are the standard ET release times (8:15, 8:30, 9:45 and 10:00 AM, 3:00 PM); the calendar's UTC stamps carry the pre-Nov 1 daylight offset
- Earnings calendar, pulled Nov 1 5:08 PM ET, Nov 2–6 premarket and after-hours reports with options-implied moves: AAPL ±3.68%, PLTR ±11.32%, AMD ±7.56%, SMCI ±12.08%, ARM ±10.45%, QCOM ±8.43%, APP ±15.02%, NET ±12.83%
- US midterm elections: Tuesday, Nov 3, 2026
- Regular-session daily closes Oct 23 and Oct 30, 2026 (quotes): SPY 759.97 to 755.72, QQQ 704.40 to 690.49, RSP 216.54 to 218.31, IWM 275.75 to 279.33, SMH 527.20 to 522.49, USO 169.53 to 168.83
- Oct 30 one-day moves vs Oct 29 close: SMH 561.67 to 522.49 (−6.98% on daily bars; −6.92% in the Oct 30 recap's 4:00 PM ET quotes), INTC −28.49%
- Daily closing moods Oct 26–30 from data/market/day-moods.json
- Chart: the same options-implied moves from the earnings calendar
- @Reuters — “Iran's IRGC Navy says two tankers 'exploded' after hitting mines in Hormuz”
- @FirstSquawk — “TWO OIL TANKERS STRUCK MINES ON AN “UNAUTHORIZED ROUTE” IN THE STRAIT OF HORMUZ - IRAN’S STATE MEDIA”
- @DeItaone — “IRAN'S NAVY SAYS OIL TANKER CATCHES FIRE IN STRAIT OF HORMUZ AFTER COLLIDING WITH NAVAL MINES - STATE MEDIA”
- @FirstSquawk — “IRANIAN NAVY REPORTS OIL TANKER FIRE IN STRAIT OF HORMUZ FOLLOWING MINE INCIDENT – STATE MEDIA”
- @FirstSquawk — “Iran vows to keep the Strait of Hormuz shut until Tehran’s demands are satisfied, security chief Rezaei says.”
- @FirstSquawk — “NETANYAHU IS PRESSING TRUMP TO RESUME STRIKES ON IRAN IMMEDIATELY AFTER TUESDAY’S U.S. MIDTERM ELECTIONS, BUT TRUMP WANTS TO GIVE DIPLOMACY MORE TIME - AXIOS”
- @Reuters — “Donald Trump said Washington was in no hurry to strike a deal with Iran and declined to say whether he expected the US to go back to war with Tehran after the midterm elections”
- @KobeissiLetter — “US private fixed investment in information processing equipment and software grew at an annualized rate of +7.3% in Q3 2026, to a record $1.77 trillion.”
Get tomorrow's brief before the open.
Weekdays at 8:30 ET. Free. Unsubscribe anytime. Privacy