- The close scored Bleeding: S&P proxy −1.78%, Nasdaq proxy −3.47%, Dow proxy −1.09%, small caps −1.64%, vol proxy +10.34%, long Treasuries +0.44%, the dollar −0.10%, crude +0.37%, gold −3.45% and Bitcoin about −1.8%.
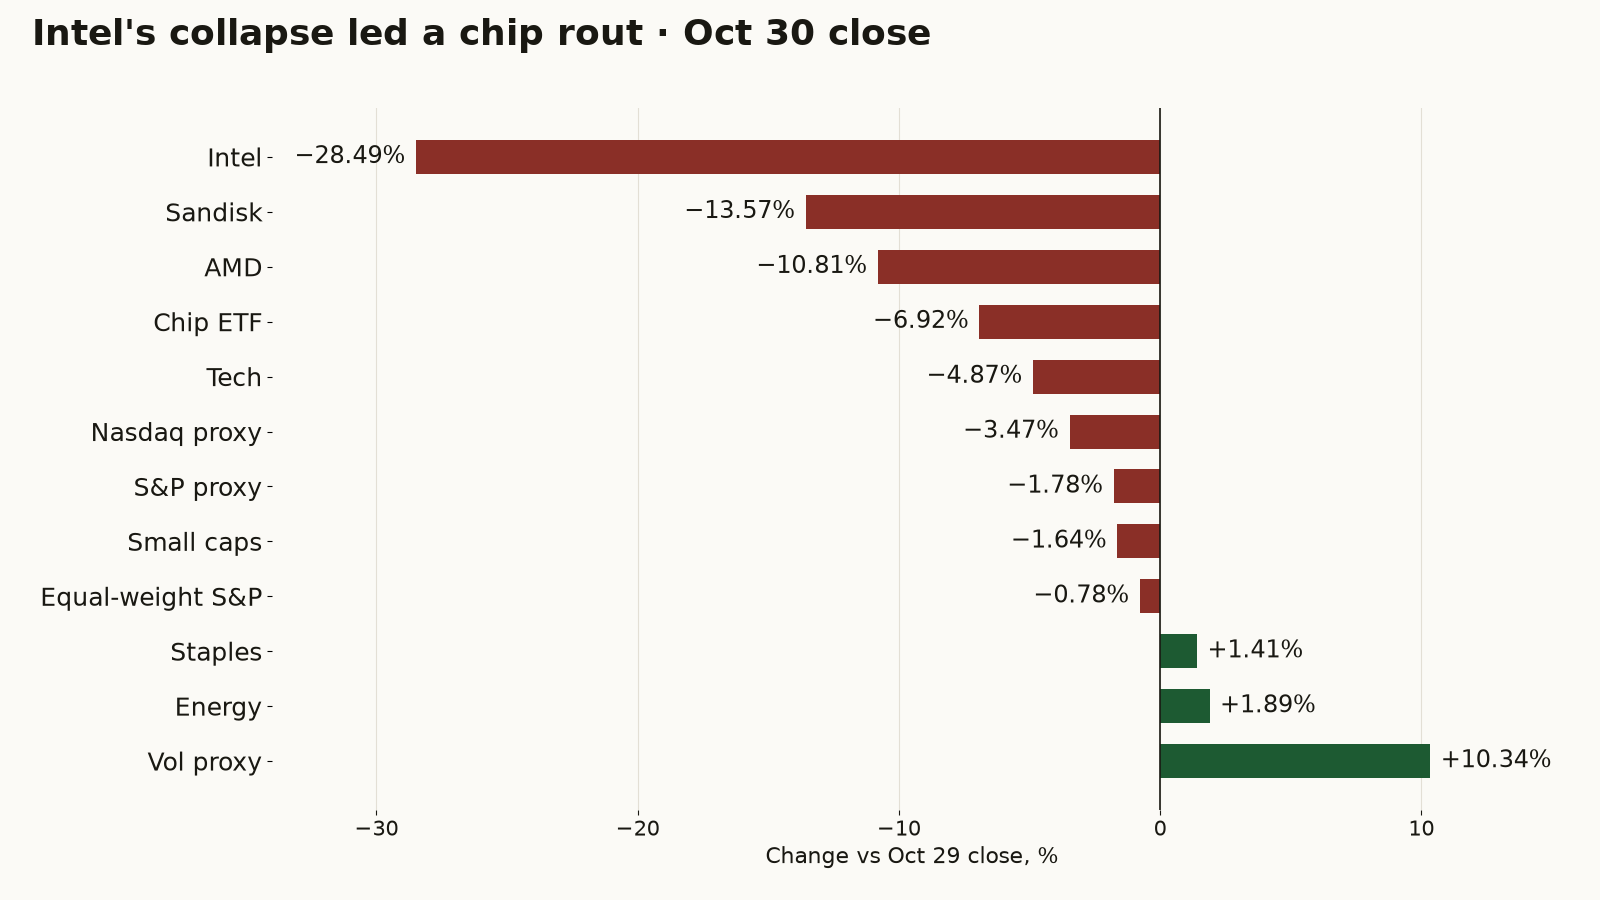
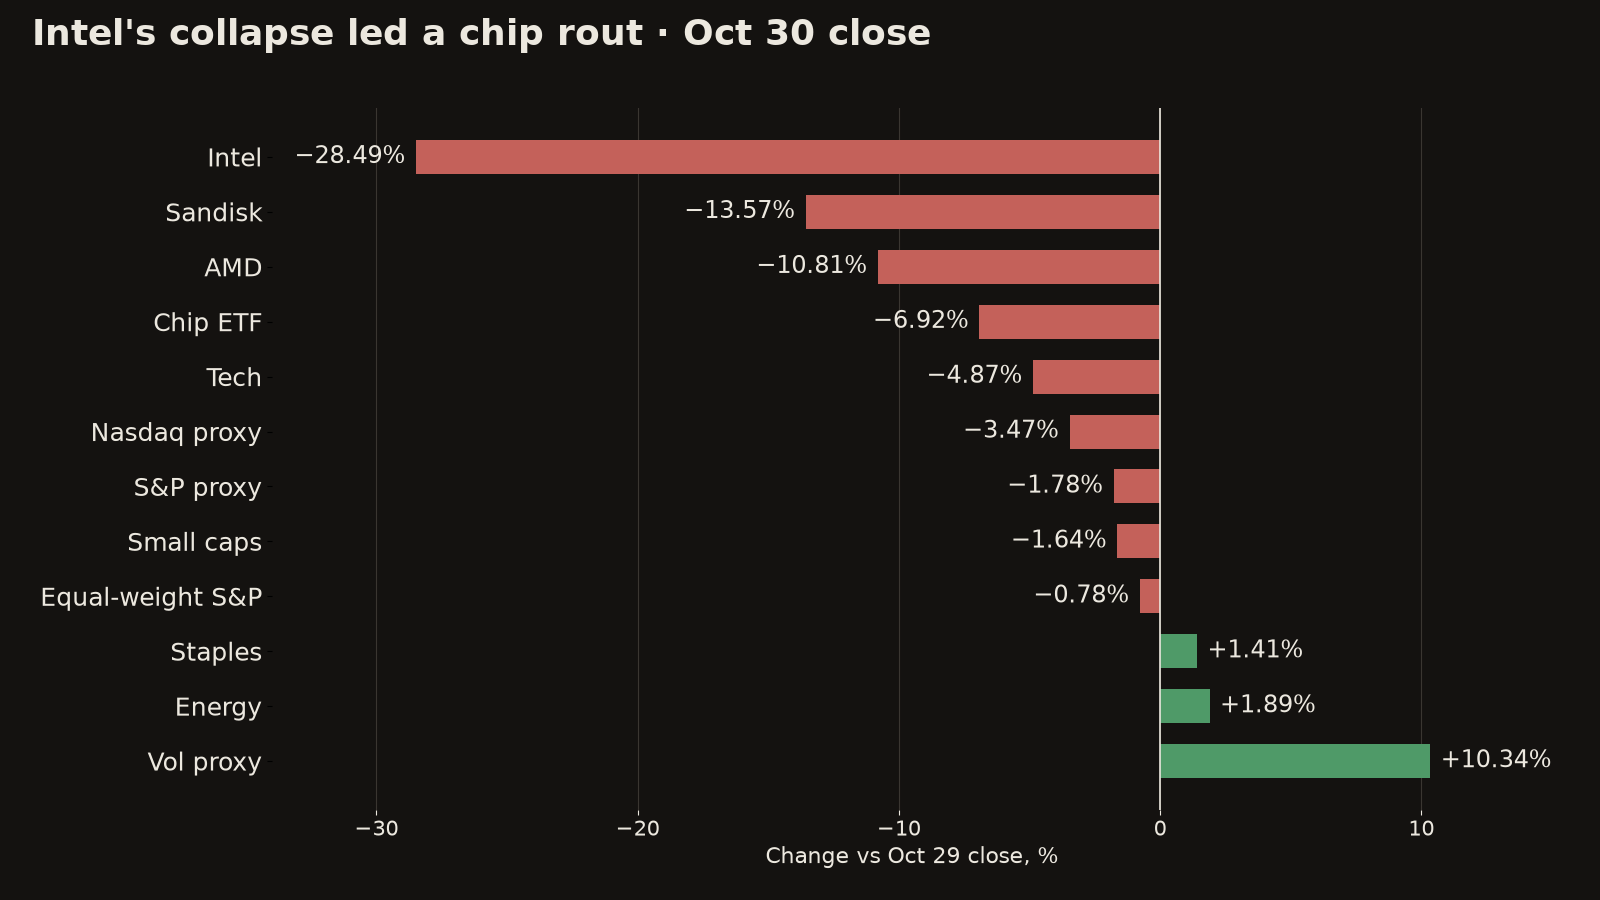
- It was a chip rout: Intel fell 28.49% on its outlook, Sandisk 13.57%, AMD 10.81% and the chip ETF 6.92%, while energy led at +1.89% on Exxon and Chevron beats and the equal-weight S&P fell only 0.78%.
- After hours is quiet, with no major reports. Monday brings ISM manufacturing at 10:00 AM ET (prior 54.5), Marriott before the open, and Apple and Palantir after the close.
Key numbers
Friday, October 30 belonged to Intel, and it dragged the whole chip complex down with it. Intel fell about 28.5% after a weak fourth-quarter outlook, which posts call its worst day in at least four decades. The chip ETF lost about 6.9%, AMD about 10.8% and Sandisk about 13.6%. The Nasdaq proxy fell about 3.5% and the S&P proxy about 1.8%, while the vol proxy jumped about 10.3%. The selling built through the morning and never let up, and the S&P proxy sat below −1.5% from late morning to the bell, which scores the close Bleeding.
This was a tech rout more than a market-wide flush. The equal-weight S&P fell only about 0.8%, a full point better than the S&P proxy, and six of eleven sector groups finished higher. Energy led at about +1.9%, staples rose about 1.4% and utilities about 0.7%, while tech fell about 4.9%. Small caps lost about 1.6% and the Dow proxy about 1.1%. Long Treasuries gained about 0.4%, crude edged up about 0.4%, the dollar slipped about 0.1% and gold fell about 3.5%.
The morning's reports were fine and mostly ignored. Exxon's street-reported adjusted earnings were $4.23 a share against the calendar's $3.90 and the stock rose about 2.2%. Chevron's were $5.28 against $4.78, up about 1.8%. AbbVie earned $3.82 against $3.74, raised its full-year outlook and rose about 1.4%. Amazon cut its after-hours loss to finish down about 1.4%.
Research
Chicago PMI came in at 55.3 in a street report, below the 56.0 posts expected and down from 58.8, with no actual posted on the calendar yet. Intel's five-year credit default swap widened to a record 123.5 basis points, per posts, so the worry reached its bonds as well as its stock. Nothing major reports after the close, and the calendar's next high-impact release is ISM manufacturing on Monday at 10:00 AM ET (prior 54.5).
What X is saying
Posts say hedge funds made their biggest risk cut on record this week, a 7.8% pullback in exposure from the peak, which fits a day when crowded chip and AI names fell hardest. Accounts report the Nasdaq 100 fell 10% from its October high, setting up a correction. Others note that Broadcom, Alphabet and Micron are each down more than 25% from their peaks. These are claims, not confirmed facts.
Insight
Two days of big-tech disappointment have turned into a test of the whole AI trade. Thursday the market sold the biggest spenders and bought everything else. Friday it sold the chipmakers, and the rest of the market held up better but still fell. The equal-weight S&P beating the S&P proxy by a point says this is still a rotation out of tech rather than a run from stocks. Monday's ISM report and Apple and Palantir after the close have to show whether that holds.
- CoolingThe AI spending boomThe chip ETF fell 6.92%, AMD 10.81% and Nvidia 4.14% as Intel's 28.49% collapse turned the market against chipmakers for a second day.
- SteadyThe average stock catching upThe equal-weight S&P fell 0.78% against the S&P proxy's 1.78%, a second day of beating the index, but small caps lost 1.64%.
- SteadyOil keeps climbingEnergy was the best group at +1.89% on Exxon and Chevron beats, while crude rose only about 0.4% despite more tanker incidents near Hormuz, accounts report.
SOURCES ›
- Economic calendar 2026-10-30: Chicago PMI 9:45 AM ET (prior 58.8, no forecast or actual posted); 2026-11-02: ISM manufacturing 10:00 AM ET (prior 54.5), S&P manufacturing PMI 9:45 AM ET (prior 55.9), construction spending 10:00 AM ET (prior 0.9%)
- Earnings 2026-10-30 before the open (EPS est): XOM (3.90), CVX (4.78), ABBV (3.74); no reports listed after the close
- Earnings 2026-11-02: MAR before the open; AAPL (1.98) and PLTR (0.41) after the close
- Quotes as of 4:00 PM ET 2026-10-30 vs 2026-10-29 closes: SPY, QQQ, IWM, DIA, RSP, SMH, TLT, VXX, UUP, USO, GLD, XLK, XLY, XLI, XLB, XLU, XLE, XLP, XLRE, XLC, XLF, XLV, INTC, SNDK, AMD, NVDA, AMZN, XOM, CVX, ABBV
- After-hours quotes as of about 5:15 PM ET vs the 4:00 PM ET close: SPY, QQQ, SMH, INTC
- Bitcoin as of 5:16 PM ET vs midnight ET
- Intraday mood refreshes Oct 30 (S&P proxy below −1.5% from about 11:40 AM ET)
- Chart: the same closing quotes for INTC, SNDK, AMD, SMH, XLK, QQQ, SPY, IWM, RSP, XLP, XLE and VXX
- @zerohedge — “*INTEL SHARES PLUNGE 29% FOR WORST DAY IN AT LEAST FOUR DECADES”
- @wallstengine — “Intel's Q3 earnings beat was overshadowed by a broad Q4 outlook miss, with revenue, EPS and gross margin forecasts all falling well below Wall Street expectations.”
- @wallstengine — “Adj. EPS: $4.23 (Est. $4.08)”
- @FirstSquawk — “CHEVRON: 3Q ADJ EPS $5.28, EST. $4.93”
- @FirstSquawk — “Q3 Adj EPS: $3.82 (est $3.74)”
- @wallstengine — “Raises FY26 Guide:”
- @FirstSquawk — “US MNI CHICAGO PMI OCT: 55.3 (EST 56.0; PREV 58.8)”
- @wallstengine — “Intel's $INTC 5-year credit default swap widens to a record high of 123.5 bps”
- @wallstengine — “Hedge funds just made their biggest risk cut on record:”
- @FirstSquawk — “NASDAQ 100 FALLS 10% FROM OCTOBER HIGH, SET TO ENTER CORRECTION”
- @DeItaone — “TECH STOCK SELLOFF: BIGGEST NAMES FALL SHARPLY FROM THEIR PEAKS”
- @FirstSquawk — “IRGC: FOURTH TANKER EXPLODES AFTER HITTING MINE IN STRAIT OF HORMUZ - IRIB”
Get tomorrow's brief before the open.
Weekdays at 8:30 ET. Free. Unsubscribe anytime. Privacy