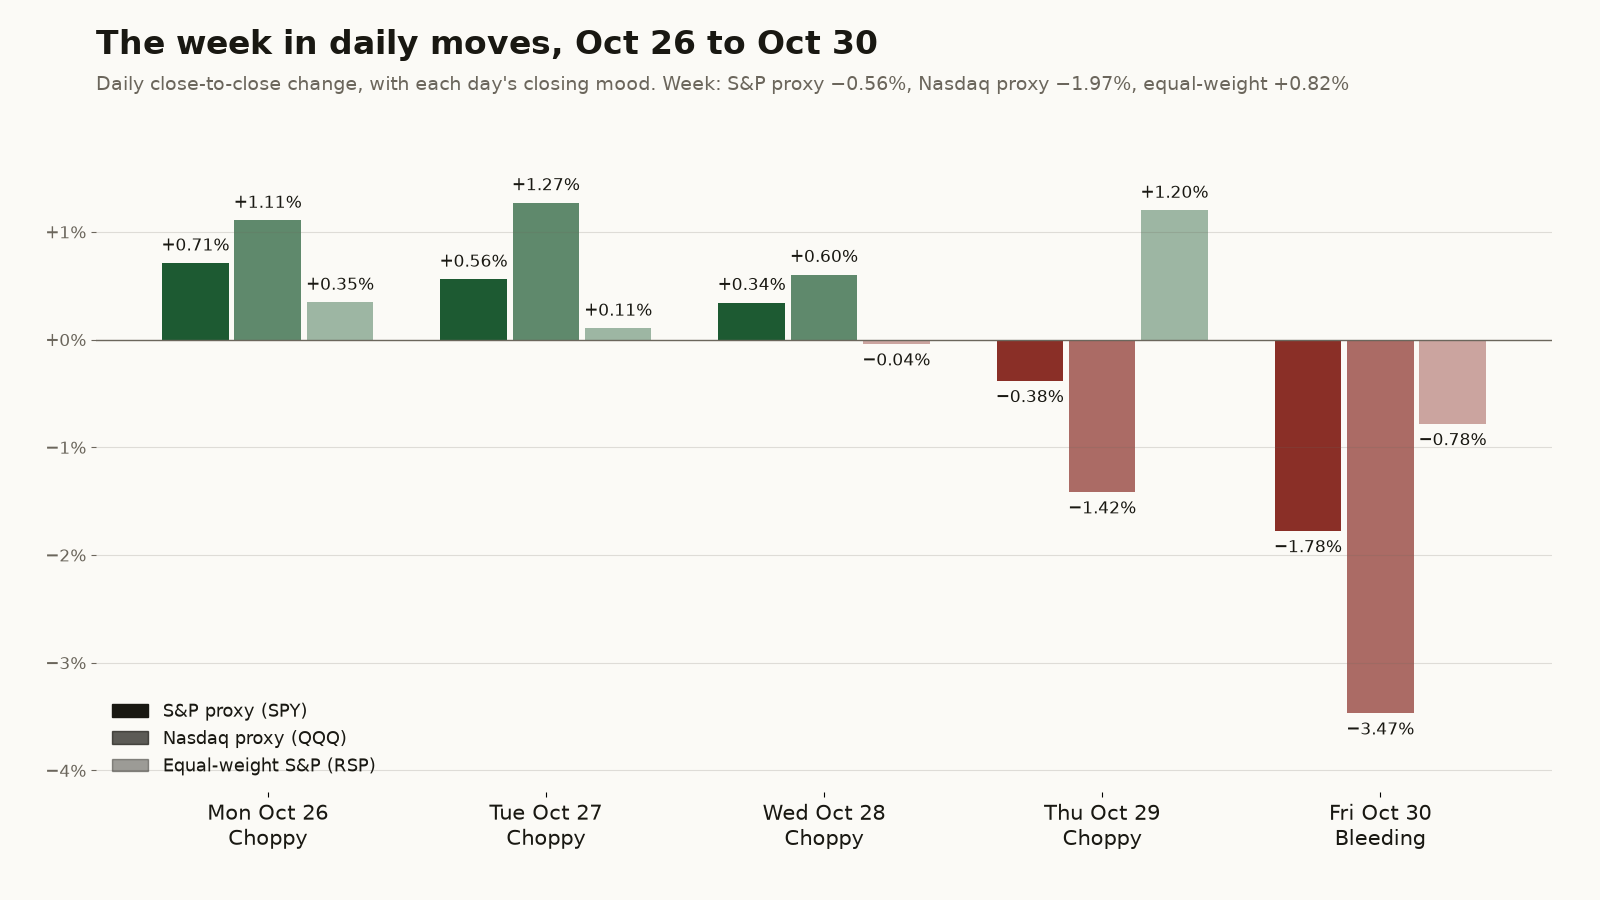
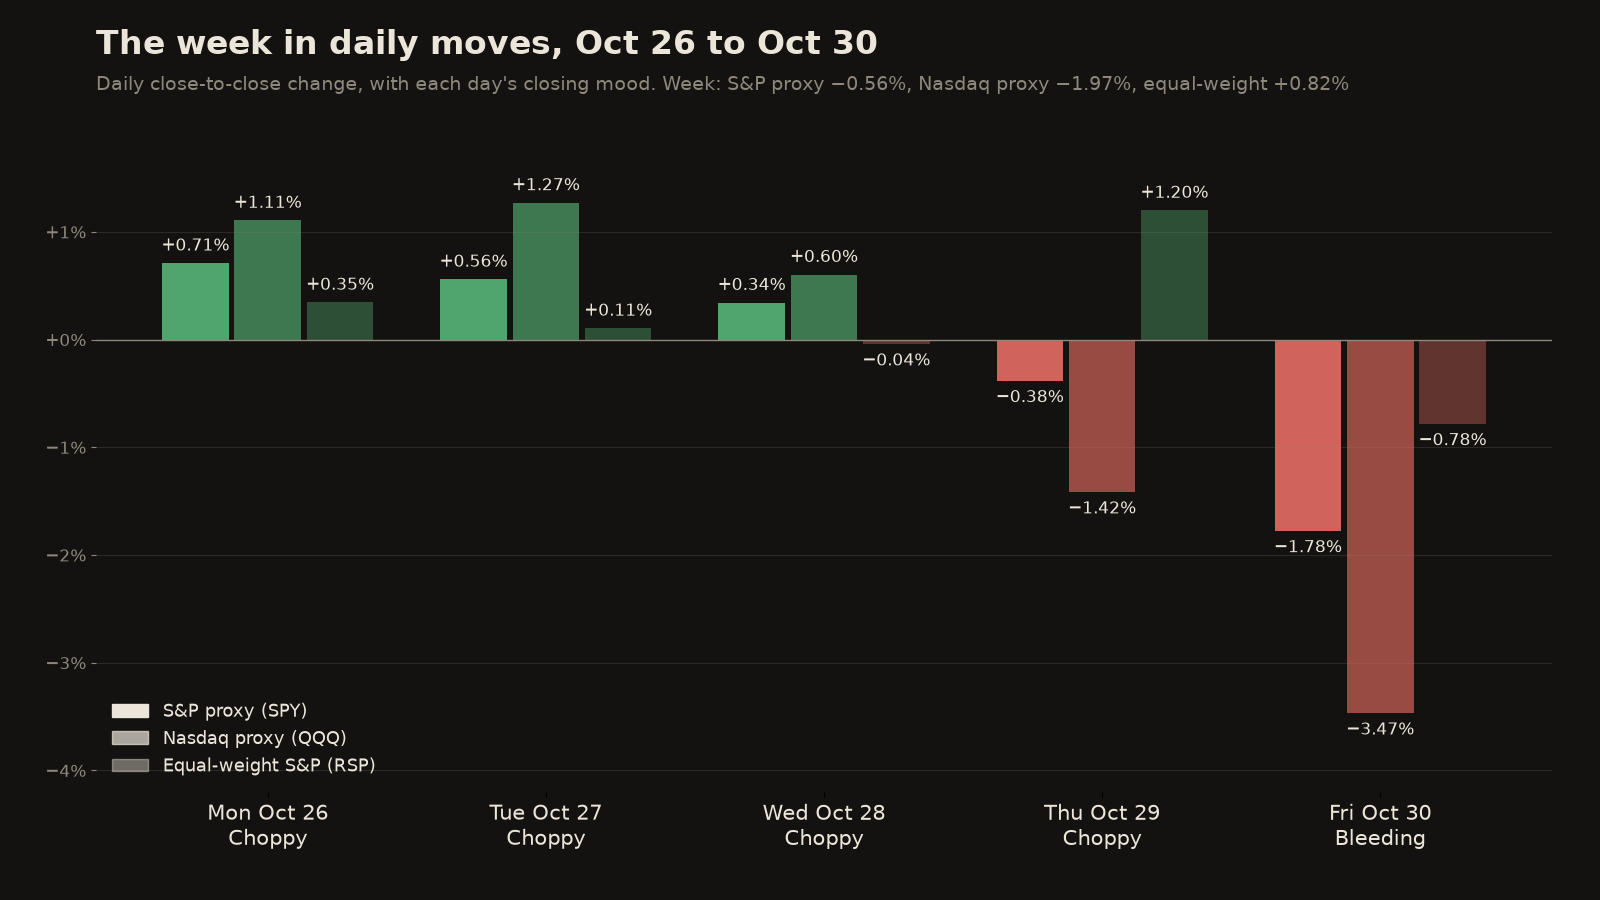
- The week in moods: Choppy Monday, Choppy Tuesday, Choppy Wednesday, Choppy Thursday and a Bleeding Friday.
- The turn came Thursday, when Alphabet's record post-earnings drop flipped big tech from leader to drag, and Intel's 28.5% plunge Friday finished the job.
- The average stock won the week: the equal-weight S&P rose 0.82% and small caps 1.31% while the S&P proxy fell 0.56% and the Nasdaq proxy 1.97%.
Key numbers
The week in moods
This was a week of four Choppy closes and one Bleeding one. The S&P proxy rose on each of the first three days, gaining about 1.6% from last Friday's close to Wednesday's, while the chip ETF climbed about 7.7%. Then Alphabet's report turned the week on Thursday, and Intel's collapse on Friday finished it. The S&P proxy ended the week down about 0.6% and the Nasdaq proxy about 2.0%, but the equal-weight S&P rose about 0.8% and small caps about 1.3%.
The week in moods
The calmest stretch was Wednesday, when the S&P proxy rose only about 0.3% and the market sat and waited for the Fed until a late move settled into a Choppy close. Monday was the best day, up about 0.7%, after Anthropic's IPO filing put numbers on chip demand. Friday was the wildest. Intel fell about 28.5% after a weak fourth-quarter outlook, the chip ETF lost about 6.9% and the Nasdaq proxy about 3.5%, and the vol proxy jumped about 10.3%. The S&P proxy sat below −1.5% from late morning to the bell, which is what made the close Bleeding.
Best and worst trades
Among the week's headline names, Vertiv was the best, up about 19.7% from last Friday, most of it on Wednesday's 16.5% jump after posts said its organic orders more than doubled. Eli Lilly rose about 11.2% after beating estimates and raising its revenue outlook. The worst was ServiceNow, down about 33.9% for the week, after it guided fourth-quarter growth below forecasts and fell about 27.0% on Thursday alone. Intel lost about 24.3%: it was up about 9.9% through Wednesday before Friday's plunge. Fortinet fell about 24.4% and Alphabet about 12.6%.
The story that won the week
The Average Stock Catching Up won. The equal-weight S&P beat the S&P proxy by about 1.4 points for the week, and it held up better on both down days, rising about 1.2% Thursday while the index fell. The AI Spending Boom cooled. It ran hot through Wednesday, then Alphabet, Amazon and Intel turned the market against the spenders and then the chipmakers, and the chip ETF gave back its whole gain to finish down about 0.8%. Posts say hedge funds made their biggest risk cut on record this week, which fits crowded tech falling hardest.
Next week's mood
Monday starts with the manufacturing PMI at 9:45 AM ET (prior 55.9), then ISM manufacturing at 10:00 AM ET (prior 54.5) and construction spending at the same time. Marriott reports before the open, and Apple and Palantir report after the close, with implied moves of about 3.7% and 11.3%. The desk expects a Rattled Monday: Friday's selling ended at the lows, and the vol proxy is up about 2.6% for the week. A firm ISM and steady chips would pull it back to Choppy, while chip losses spreading into the rest of the market would keep it Bleeding.
- SteadyThe average stock catching upThe equal-weight S&P rose 0.82% and small caps 1.31% for the week while the S&P proxy fell 0.56%, a 1.38-point gap.
- CoolingThe AI spending boomThe chip ETF rose 7.68% through Wednesday, then fell about 7.9% over Thursday and Friday to end the week −0.83%.
SOURCES ›
- Economic calendar, pulled 5:50 PM ET 2026-10-30: 2026-11-02 US manufacturing PMI 9:45 AM ET (prior 55.9), ISM manufacturing PMI 10:00 AM ET (prior 54.5), construction spending 10:00 AM ET (prior 0.9%); no forecasts posted
- Earnings calendar 2026-11-02: MAR before the open (expected move about 3.9%); AAPL (EPS est 1.98, expected move about 3.7%) and PLTR (EPS est 0.41, expected move about 11.3%) after the close
- Daily closing bars 2026-10-23 to 2026-10-29 and 4:00 PM ET closing quotes 2026-10-30: SPY, QQQ, IWM, RSP, SMH, VXX, DIA, VRT, LLY, NOW, INTC, FTNT, GOOGL
- Week changes are Fri Oct 30 close vs Fri Oct 23 close; daily changes close to close
- Closing moods from data/market/day-moods.json, 2026-10-26 to 2026-10-30; intraday mood refreshes Oct 28 and Oct 30
- Chart: the same daily closes for SPY, QQQ and RSP
- @wallstengine — “Organic Orders Growth: 100%+”
- @FirstSquawk — “ELI LILLY Q3 2026 EARNINGS - REV: $24.40B (EST $22.52B) - ADJ EPS: $7.48 (EST $5.59)”
- @wallstengine — “Revenue: $91.0B-$92.0B (Est. $88.85B) 🟢; from $85B-$87B”
- @wallstengine — “ServiceNow expects growth to slow to 18.5% in Q4, below Street's 19.7% estimate”
- @wallstengine — “Intel's Q3 earnings beat was overshadowed by a broad Q4 outlook miss, with revenue, EPS and gross margin forecasts all falling well below Wall Street expectations.”
- @wallstengine — “Alphabet $GOOGL -13%, on track for its WORST post-earnings decline on record”
- @wallstengine — “Hedge funds just made their biggest risk cut on record:”
Get tomorrow's brief before the open.
Weekdays at 8:30 ET. Free. Unsubscribe anytime. Privacy