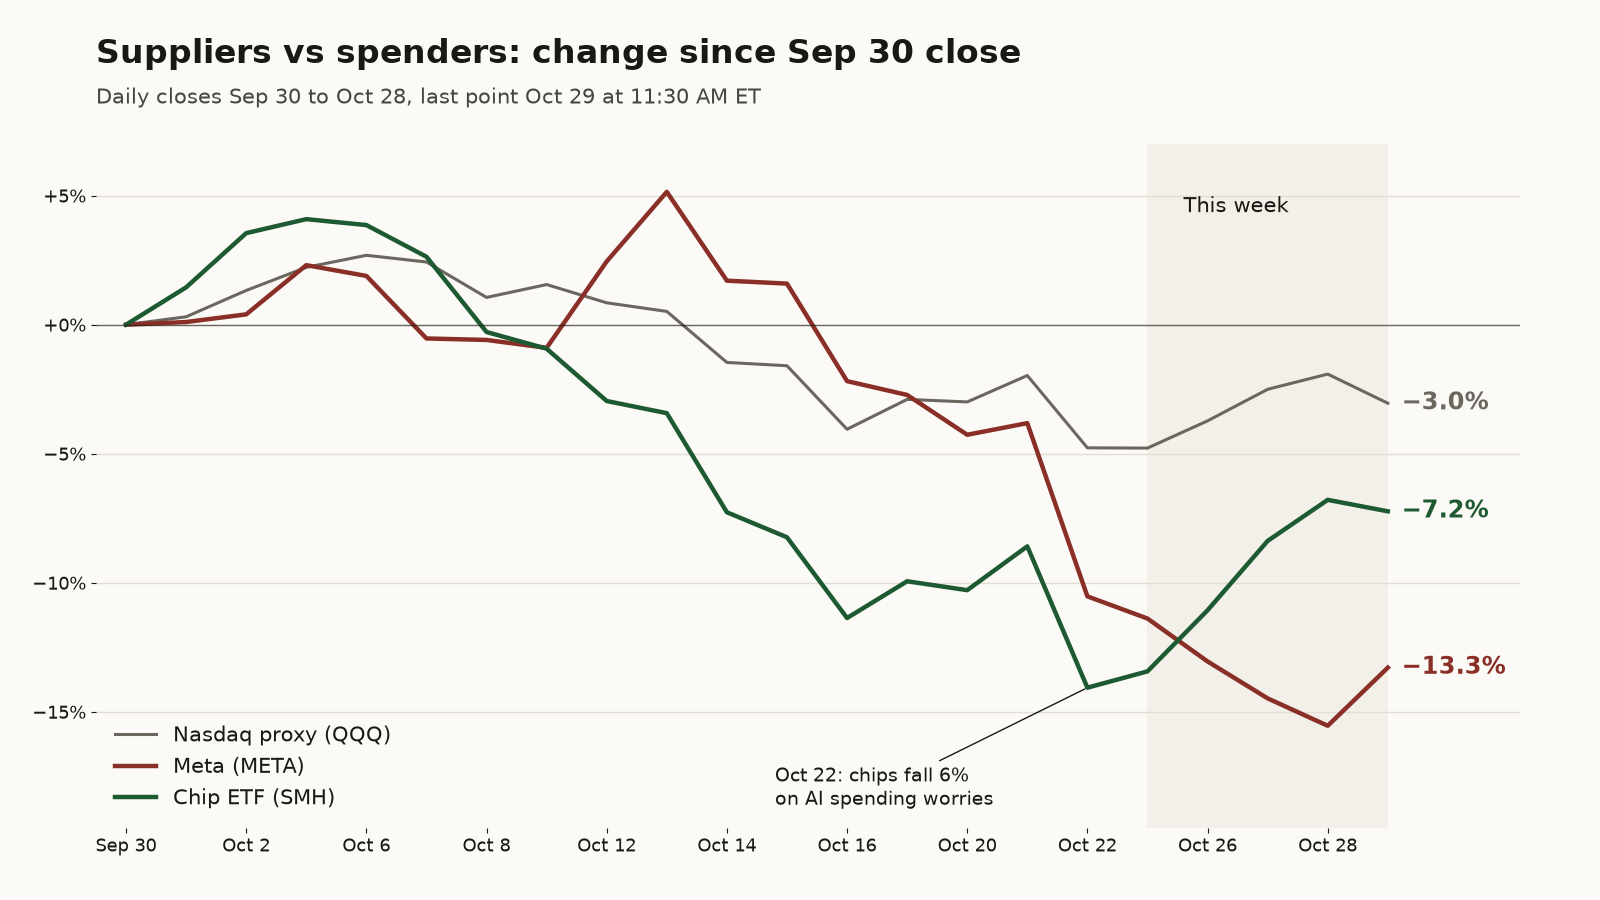
- The AI spending boom is back after last week's scare: the chip ETF is up about 7.2% this week, but the companies paying for it are falling, with Alphabet off about 11.7% today.
- Bull: Alphabet kept its $195 billion to $205 billion spending range and says 2027 rises significantly. Bear: the market is punishing the spenders, and posts say Microsoft and Alphabet both spent less than expected last quarter.
- Amazon reports after the close today with an implied move of about 6.8%, then AMD on Nov 3 and Nvidia on Nov 18.
Key numbers
The AI spending boom had its biggest week of the earnings season, and it ended with a split verdict. As of 11:30 AM ET Thursday the chip ETF is up about 7.2% since last Friday's close, with AMD up about 10.9% and Lam Research about 13.0%, a sharp rebound from the Oct 22 drop of about 6% on spending worries. The companies doing the spending are another story: Alphabet is down about 11.7% today and Meta about 13.3% since the end of September. So the question for the story we track as The AI spending boom is whether it is slowing, or just getting harder to pay for.
The bull case
Nobody cut the plan in a way that matters. Accounts report Alphabet kept its full-year spending range at $195 billion to $205 billion, and its finance chief said spending will increase significantly in 2027 and that it is renting outside computing power because it is short of capacity. Microsoft's calendar-year figure slipped to about $170 billion from about $175 billion, but posts tie that to delayed deliveries from outside suppliers, not weaker demand, and its Azure cloud grew 48%. Accounts report Microsoft is preparing a bond sale of at least $25 billion to fund the buildout, and Carrier said it signed a data-center cooling deal with one of the big spenders worth more than $3 billion. The suppliers' stocks agree: the chip ETF is up about 8.0% from its Oct 22 close, and options flow data showed about $13 million of net call buying in the chip ETF on Wednesday.
The bear case
The spending is real, but investors are questioning the payoff, and the bill is moving to the bond market. Posts say both giants spent less than expected last quarter: about $51.4 billion at Alphabet against $55.2 billion expected, and about $39.4 billion at Microsoft against $45.9 billion. Investors sold Alphabet anyway on search and ad misses, and Meta fell about 7.0% the day after its Oct 21 report and has kept sliding. Accounts report ECB President Christine Lagarde said debt sales by the biggest spenders play a role in rising yields. And in the biggest chip name the money is cautious: options flow data shows net selling of Nvidia calls of about $21 million Wednesday and about $20 million more by late morning Thursday. Nvidia is up only about 1.6% this week, far behind the rest of the chip ETF. Flow is a clue, not a signal.
What would settle it
Four reports in the next three weeks. Amazon reports after the close today with an implied move of about 6.8%, and its spending plan for next year is the first test. Apple follows on Nov 2 (implied about 3.4%), AMD on Nov 3 (about 7.2%) and Nvidia on Nov 18 (about 7.3%). On the tape, the story's own end condition is chip stocks falling on good reports. If the chip ETF slides back toward its Oct 22 close near 523 after strong numbers, the bear case wins. A close back above its Oct 5 level near 634 would say last week's scare is fully over.
Desk read
The evidence leans bull, with moderate confidence. The spending plans held, the biggest spenders are borrowing to keep them, and the suppliers rallied hardest this week. What changed is who pays: the market is charging the spenders, not the chipmakers, for the bill. That split, with Meta and Alphabet down while AMD and Lam Research rise, is the thing to watch. If Amazon lifts its spending tonight and chips rise with it, the split widens in the bulls' favor. If chips fall on good news from Amazon and AMD, the story is cooling for real. This is a read of the evidence, not a trade call.
- SteadyThe AI spending boomThe chip ETF is up about 7.2% this week while Alphabet fell about 11.7% today and Meta is down about 13.3% since Sep 30, so the story is intact for suppliers but costly for spenders.
SOURCES ›
- Earnings afterhours 2026-10-29: AMZN (EPS est 2.01, implied move ~6.8%), INTC (0.39, ~7.3%) (earnings calendar, pulled 11:31 AM ET Oct 29)
- Upcoming earnings: AAPL 2026-11-02 postmarket (implied ~3.4%), AMD 2026-11-03 postmarket (implied ~7.2%), NVDA 2026-11-18 (implied ~7.3%) (earnings calendar, pulled Oct 29)
- Past reports: META 2026-10-21 postmarket, next-day move −6.98%; LRCX 2026-10-21 postmarket, next-day move −11.76% (earnings history)
- Quotes at about 11:30 AM ET Oct 29 vs Oct 28 close: SMH 564.96 (−0.48%), GOOGL 286.98 (−11.67%), MSFT 523.51 (−1.41%), AMZN 248.40 (−2.44%), META 628.83 (+2.67%), NVDA 214.28, AMD 573.12, LRCX 259.90, QQQ 717.26
- Daily closes Oct 23: SMH 527.20, AMD 516.79, LRCX 230.10, NVDA 210.96, META 642.62, QQQ 704.40; week changes to 11:30 AM ET Oct 29: SMH +7.16%, AMD +10.90%, LRCX +12.95%, NVDA +1.57%, META −2.15%
- Daily closes Sep 30: SMH 609.00, META 725.18, QQQ 739.77; changes to 11:30 AM ET Oct 29: SMH −7.23%, META −13.29%, QQQ −3.04%. SMH Oct 5 close 633.90, Oct 22 close 523.35 (+7.95% since); SMH Oct 22 close was −14.06% vs Sep 30; META Oct 28 close −15.54% vs Sep 30
- Options flow data, daily options volume: SMH Oct 28 net call premium +$13.0M, net put premium −$10.5M; NVDA Oct 28 net call premium −$20.9M, net put premium +$19.4M; NVDA Oct 29 through about 11:30 AM ET net call premium −$20.1M
- Mood Choppy per data/market/hero.json, 9:56 AM ET Oct 29 refresh
- @wallstengine — “$GOOGL STILL SEES FY CAPEX $195B TO $205B, EST. $202.21B”
- @wallstengine — “Expect our CapEx to increase significantly in 2027”
- @wallstengine — “Given the supply constraint environment, we started utilizing third-party compute capacity at the end of Q3, and will ramp usage in Q4.”
- @wallstengine — “CY26 CapEx: ~$170B, lowered on 3rd-party capacity delays (Prior: ~$175B)”
- @FirstSquawk — “MICROSOFT Q1 CLOUD REVENUE $63.9 BLN, ABOVE ESTIMATE OF $61.62 BLN, WITH AZURE REVENUE EX-FX UP 48%, ABOVE ESTIMATE OF +44.8%, AND CAPEX $39.37 BLN, BELOW ESTIMATE OF $45.93 BLN”
- @wallstengine — “CapEx: $51.4B (Est. $55.2B)”
- @wallstengine — “$MSFT is looking to raise at least $25B through a 10-part U.S. bond offering, as it joins other major tech companies tapping debt markets to finance the AI infrastructure buildout.”
- @wallstengine — “Earlier this month, we signed an agreement with a hyperscaler for more than $3 billion.”
- @DeItaone — “ECB'S LAGARDE: DEBT ISSUANCE BY HYPERSCALERS PLAYS A ROLE IN YIELD RISE”
Get tomorrow's brief before the open.
Weekdays at 8:30 ET. Free. Unsubscribe anytime. Privacy