- Last week went Grinding, Calm, Grinding, Rattled, Choppy, and oil won it: crude rose about 4.8% and small caps about 2.0% while the S&P proxy slipped about 0.4% and the chip ETF fell about 2.3%.
- The week's question is whether big tech's AI spending can carry stocks past a Fed that raised rates in September and crude above $100. Wednesday answers it, with the Fed decision at 2:00 PM ET and Microsoft and Alphabet after the close.
- Monday is light: no major economic release on the calendar, Verizon before the open, and Welltower, Cadence Design and Nucor after the close.
Key numbers
The week ahead
- VZ BMO · WELL AMC · CDNS AMC · NUE AMC · PSA AMC
- Fed meeting begins (target range 3.75% to 4%)
- KO BMO · BA BMO · UPS BMO · PYPL BMO · V AMC · STX AMC · HOOD AMC · NXPI AMC
- 2:00 PM Fed rate decision (prior: raised 0.25 point to 3.75% to 4% on Sep 16)
- GEV BMO · ADP BMO · VRT BMO · MSFT AMC · GOOGL AMC · NOW AMC · KLAC AMC · FTNT AMC
- 8:30 AM Q3 GDP, advance (prior +2.2% annualized)
- 8:30 AM September personal income and spending, PCE prices (prior +3.4% y/y)
- LLY BMO · MA BMO · CAT BMO · MRK BMO · AMZN AMC · INTC AMC · SNDK AMC · SBUX AMC
- XOM BMO · CVX BMO · ABBV BMO · AZN BMO
Last week ran Grinding, Calm, Grinding, Rattled and Choppy. The S&P proxy finished down about 0.4%, but the averages hid a split: crude rose about 4.8% and small caps about 2.0%, while the chip ETF fell about 2.3% after Thursday's AI selloff. Now comes the busiest stretch of the earnings season, wrapped around a Fed meeting. The question is simple: can big tech's spending story carry the market past a Fed that is still fighting inflation and oil above $100?
The week's question
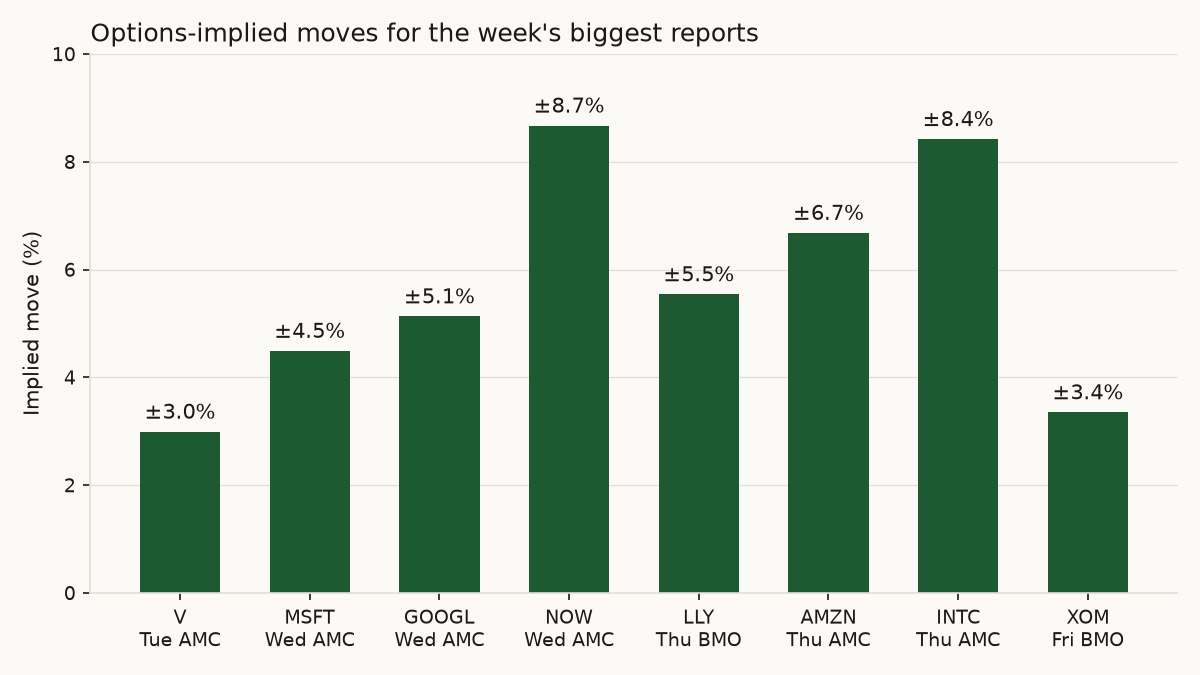
Wednesday answers it. The Fed announces its decision at 2:00 PM ET, six weeks after it raised its target range by a quarter point to 3.75% to 4%. A few hours later Microsoft and Alphabet report, with options pricing moves of about 4.5% and 5.1%. Amazon and Intel follow Thursday after the close, priced for about 6.7% and 8.4%, on the same morning as third-quarter GDP and September inflation at 8:30 AM ET. If the Fed sounds no worse than September and the cloud numbers hold up, chips have room to win back last week's losses. If the Fed leans toward another hike while crude stays high, Thursday's inflation print carries more weight than any report.
Stories in play
The AI spending boom is the one most on trial. Thursday's drop in the chip ETF came the day after Meta's report sent Meta down about 7%, and Microsoft, Alphabet and Amazon now get to say whether their own data center budgets are still growing. Oil keeps climbing enters the week with crude near $103 a barrel, and Exxon and Chevron close the week on Friday morning. Long yields near the highs gets its test from the Fed and Thursday's inflation data; long Treasuries rose about 1.6% last week, so yields eased even as oil rose.
What X is saying
The weekend was about Iran. Posts on Saturday said Trump warned the US could attack Iran again, and on Sunday accounts reported him saying the US will not strike Iran today. Accounts also reported Brent hitting $116.72, its highest since April, and posts cited a record number of ship attacks in the Strait of Hormuz this month. On the calendar side, posts call this one of the busiest weeks of the year, with about a fifth of S&P 500 companies reporting, and accounts cite reports that the Fed is expected to hold. These are claims from posts, not confirmed facts.
Desk stance for Monday
The desk goes into Monday Waiting. Monday has no major release and only a handful of reports, so the open will mostly trade the weekend's Iran headlines through crude. A calm open with oil steady keeps the tape in waiting mode until Wednesday. A fresh jump in crude on new strike talk would lean Choppy, with energy up and consumer names and banks heavy, as on Friday.
- SteadyThe AI spending boomThe chip ETF fell about 2.3% last week, and Microsoft, Alphabet, Amazon and Intel report Wednesday and Thursday, the story's biggest test this quarter.
- HeatingOil keeps climbingCrude rose about 4.8% on the week to near $103, and weekend posts put Brent at $116.72 on Iran strike talk; Exxon and Chevron report Friday.
- SteadyLong yields near the highsLong Treasuries rose about 1.6% last week, easing yields, ahead of Wednesday's Fed decision and Thursday's PCE prices (prior +3.4% y/y).
SOURCES ›
- Federal Reserve FOMC calendar: Oct 27–28, 2026 meeting; Sep 16, 2026 statement (released 2:00 p.m. EDT) raised the target range by 1/4 point to 3-3/4 to 4 percent
- BEA release schedule: GDP (Advance Estimate) Q3 2026 and Personal Income and Outlays, September 2026, both Oct 29, 8:30 AM ET; prior Q2 GDP +2.2% (third estimate), PCE price index Aug 2026 +3.4% y/y
- Earnings calendar, pulled Oct 25 5:07 PM ET, Oct 26–30 premarket and after-hours reports with options-implied moves: MSFT ±4.49%, GOOGL ±5.13%, AMZN ±6.68%, INTC ±8.42%, NOW ±8.67%, V ±2.99%, LLY ±5.54%, XOM ±3.35%, CVX ±3.31%
- Economic calendar returned no entries for Oct 26–30 as of Oct 25 5:07 PM ET; release dates above are from official agency schedules
- Regular-session daily closes Oct 16 and Oct 23, 2026 (daily bars from the options data feed; broker quotes were unreachable at 5:10 PM ET Oct 25): SPY 763.25 to 759.97, QQQ 709.80 to 704.40, SMH 539.79 to 527.20, USO 161.76 to 169.53, IWM 270.44 to 275.75, TLT 80.05 to 81.34
- Daily closing moods Oct 19–23 from data/market/day-moods.json
- Meta post-earnings one-day move −6.98% after its Oct 21 report (earnings history)
- @FirstSquawk — “Trump Warns US Could Attack Iran as Tehran Denies Offering Deal to Reopen Strait of Hormuz”
- @FirstSquawk — “Trump: We will not strike Iran today”
- @KobeissiLetter — “President Trump announces that the US will not strike Iran today.”
- @FirstSquawk — “BRENT CRUDE HITS $116.72, HIGHEST SINCE APRIL, AMID RISING MIDDLE EAST TENSIONS”
- @Reuters — “Ship attacks in Strait of Hormuz hit record high in October”
- @FirstSquawk — “US CRUDE OIL FUTURES SETTLE AT $103.27/BBL, UP $3.80, 3.82%”
- @KobeissiLetter — “~20% of S&P 500 Companies Report Earnings This Week”
- @FirstSquawk — “US Fed expected to hold rates steady days ahead of U.S. midterms”
Get tomorrow's brief before the open.
Weekdays at 8:30 ET. Free. Unsubscribe anytime. Privacy