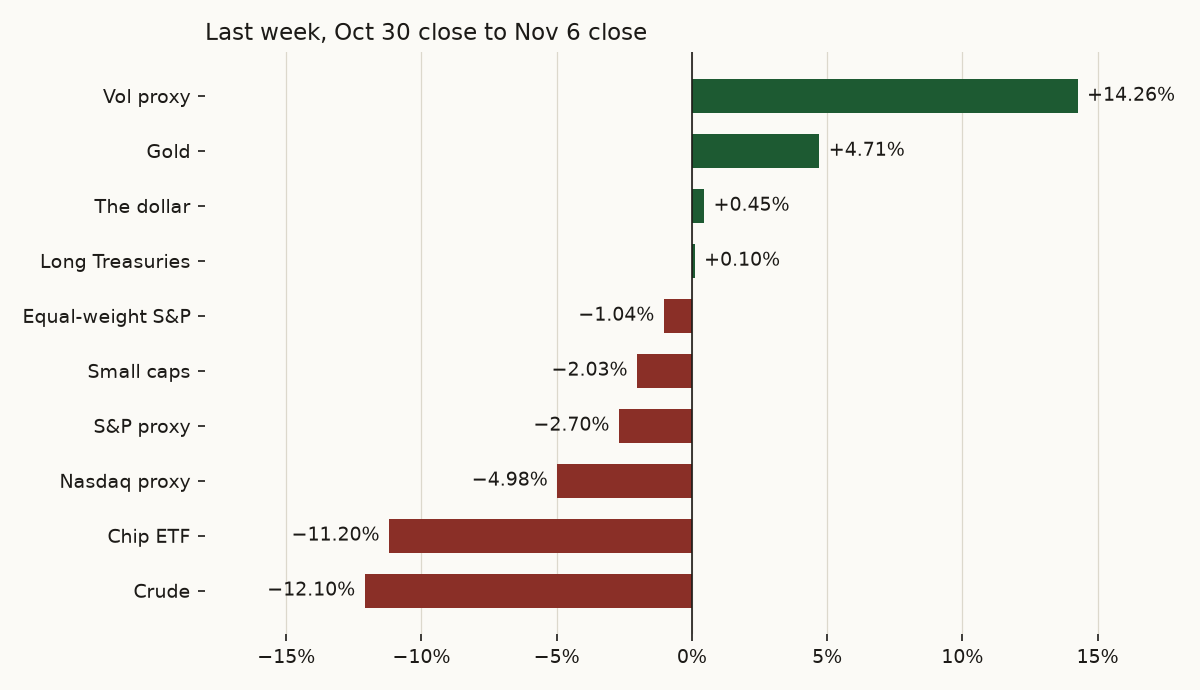
- Last week went Choppy, Choppy, Euphoric, Bleeding, Choppy, and the chip washout won it: the chip ETF fell about 11.2%, the Nasdaq proxy about 5.0% and the S&P proxy about 2.7%, while the equal-weight S&P lost only about 1.0% and gold rose about 4.7%.
- The week's question is whether the S&P proxy can hold Thursday's low and its 200-day average when October CPI prints Tuesday at 8:30 AM ET (prior core +0.3% month over month). CoreWeave after Tuesday's close (implied move ±18.1%), then Cisco and Applied Materials Thursday after the close, test the chip bounce.
- Monday has Chicago Fed President Austan Goolsbee at 10:00 AM ET, KKR, Constellation Energy and Ferguson before the open, and Occidental, Take-Two and Rocket Lab after the close.
Key numbers
The week ahead
- 6:00 AM Small business optimism (prior 97.9)
- 8:30 AM October CPI (prior +0.6% m/m, 3.7% y/y)
- 8:30 AM Core CPI (prior +0.3% m/m, 2.6% y/y)
- TDG BMO · SE BMO · CRWV AMC · PBR AMC
- 8:30 AM October PPI (prior +1.3% m/m)
- 8:30 AM Core PPI (prior +0.7% m/m)
Get the Desk's features and the market mood in your inbox. Free.
One feature a day, every day. Free. Unsubscribe anytime.
Last week broke the chart. The S&P proxy lost about 2.7% and the Nasdaq proxy about 5.0%, and the chip ETF fell about 11.2% after Thursday's washout, with Friday's Choppy bounce on hot payrolls recovering only part of it. Gold gained about 4.7%, the vol proxy about 14.3%, and crude gave back about 12.1%. So this week asks one thing: does the bounce survive the inflation data?
The week's question
Can the S&P proxy hold its 200-day average when October CPI prints Tuesday at 8:30 AM ET? The S&P 500 closed Friday at 7,376.86, about 27 points above Thursday's 7,350 low, with its 200-day average at 7,325 just underneath. Payrolls of 165,000 against 55,000 on the calendar put rate hikes back in the conversation, so a core reading above the prior +0.3% month over month would hit a market already leaning on that line. A cooler core print would let the chip bounce stand and give the average stock room. Tuesday answers it, and CoreWeave after the close adds the AI read, with options pricing a move of about 18.1%.
Stories in play
The AI spending boom (heating) meets its test twice: CoreWeave on Tuesday after the close, then Nebius before the open Thursday and Cisco and Applied Materials after the close, with implied moves from about 8.2% to 16.4%. The average stock catching up (cooling) gets a CPI check, since the equal-weight S&P fell less than the Nasdaq proxy last week but lagged on Friday's bounce. Long yields near the highs (played out) wakes up only if CPI or Friday's producer prices surprise, with the 10-year street-reported near 4.9% after the jobs print.
What X is saying
Posts say the weekend's focus is inflation. One widely shared post on Sunday asks whether record profit margins get squeezed if Friday's producer prices run hotter than Tuesday's CPI, which makes the two reports a pair for traders. That is talk, not confirmed fact; the calendar and the quotes are the facts. The desk has not seen an official account or two reputable outlets confirm any weekend news that changes the calendar.
Desk stance for Monday
The desk expects Monday to open Choppy. Goolsbee at 10:00 AM ET is the only scheduled catalyst before CPI, and with KKR and Constellation Energy before the open and Occidental, Take-Two and Rocket Lab after the close, nothing on the Monday calendar is likely to move the whole index. The tone would turn Rattled if the S&P proxy slips under Thursday's low before Tuesday, and Grinding if the equal-weight S&P starts keeping pace with the chips.
- HeatingThe AI spending boomThe chip ETF fell about 11.2% last week and rose about 3.6% on Friday; CoreWeave Tuesday (about ±18.1%) and Cisco and Applied Materials Thursday are the week's reports.
- CoolingCan the average stock catch up?The equal-weight S&P fell about 1.0% last week against about 5.0% for the Nasdaq proxy, but slipped about 0.4% on Friday while the index rose; CPI tests whether breadth can hold.
- Played outHike bets weigh on long bondsLong Treasuries rose about 0.1% last week and were flat Friday, but hot payrolls and Tuesday's CPI could wake the story if yields move.
SOURCES ›
- Economic calendar, pulled 5:02 PM ET 2026-11-08: Mon 11/9 10:00 AM ET Chicago Fed President Goolsbee speaks and wholesale trade (prior +0.5%); Tue 11/10 6:00 AM ET small business optimism (prior 97.9), 8:30 AM ET October CPI (prior +0.6% m/m, 3.7% y/y) and core CPI (prior +0.3% m/m, 2.6% y/y); Thu 11/12 8:30 AM ET weekly jobless claims, 9:00 AM ET Cleveland Fed President Hammack, 10:00 AM ET existing home sales (prior 4.0M); Fri 11/13 8:30 AM ET October PPI (prior +1.3% m/m, ex-food and energy +0.7% m/m). No forecasts posted. Nothing scheduled Wed 11/11.
- Earnings calendar, pulled 5:02 PM ET 2026-11-08, expected moves: Mon 11/9 BMO KKR (4.95%), CEG (5.89%), FERG, NRG, AMC OXY (4.74%), TTWO (7.83%), RKLB (12.45%), ASTS; Tue 11/10 BMO TDG, SE, AMC CRWV (18.10%), PBR; Wed 11/11 BMO GIB, AMC FNV; Thu 11/12 BMO BN, NBIS (16.37%), AMC CSCO (8.18%), AMAT (9.31%), NU; Fri 11/13 none of note.
- Closing quotes 4:00 PM ET 2026-11-06 vs 2026-10-30 closes: SPY 735.29 vs 755.72 (−2.70%), QQQ 656.10 vs 690.49 (−4.98%), IWM 273.67 vs 279.33 (−2.03%), RSP 216.05 vs 218.31 (−1.04%), SMH 463.96 vs 522.49 (−11.20%), TLT 81.92 vs 81.84 (+0.10%), VXX 21.95 vs 19.21 (+14.26%), USO 148.41 vs 168.83 (−12.10%), UUP 29.13 vs 29.00 (+0.45%), GLD 372.52 vs 355.78 (+4.71%). Friday moves: SMH +3.62%, RSP −0.38%, TLT −0.01%.
- S&P 500 close 7,376.86 on 2026-11-06, Thursday's low 7,350.35 and 200-day average 7,325.05, from the desk's Spaghetti Saturday 2026-11-07 levels (index daily bars to the Nov 6 close).
- Payrolls 165,000 vs 55,000 on the calendar and the 10-year yield near 4.9%, street-reported, from the desk's recap 2026-11-06.
- Week moods from the desk's day-moods record: Choppy, Choppy, Euphoric, Bleeding, Choppy.
- @zerohedge — “PPI Vs CPI: Are Record Profit Margins About To Get Squeezed?”
Get tomorrow's feature in your inbox.
One feature a day, every day. Free. Unsubscribe anytime. Privacy