- The close scored Choppy: S&P proxy +0.33%, Nasdaq proxy +1.41%, Dow proxy −0.40%, small caps +0.98%, vol proxy −1.17%, long Treasuries flat, the dollar +0.78%, crude +0.13%, gold −0.78% and Bitcoin about +0.4%.
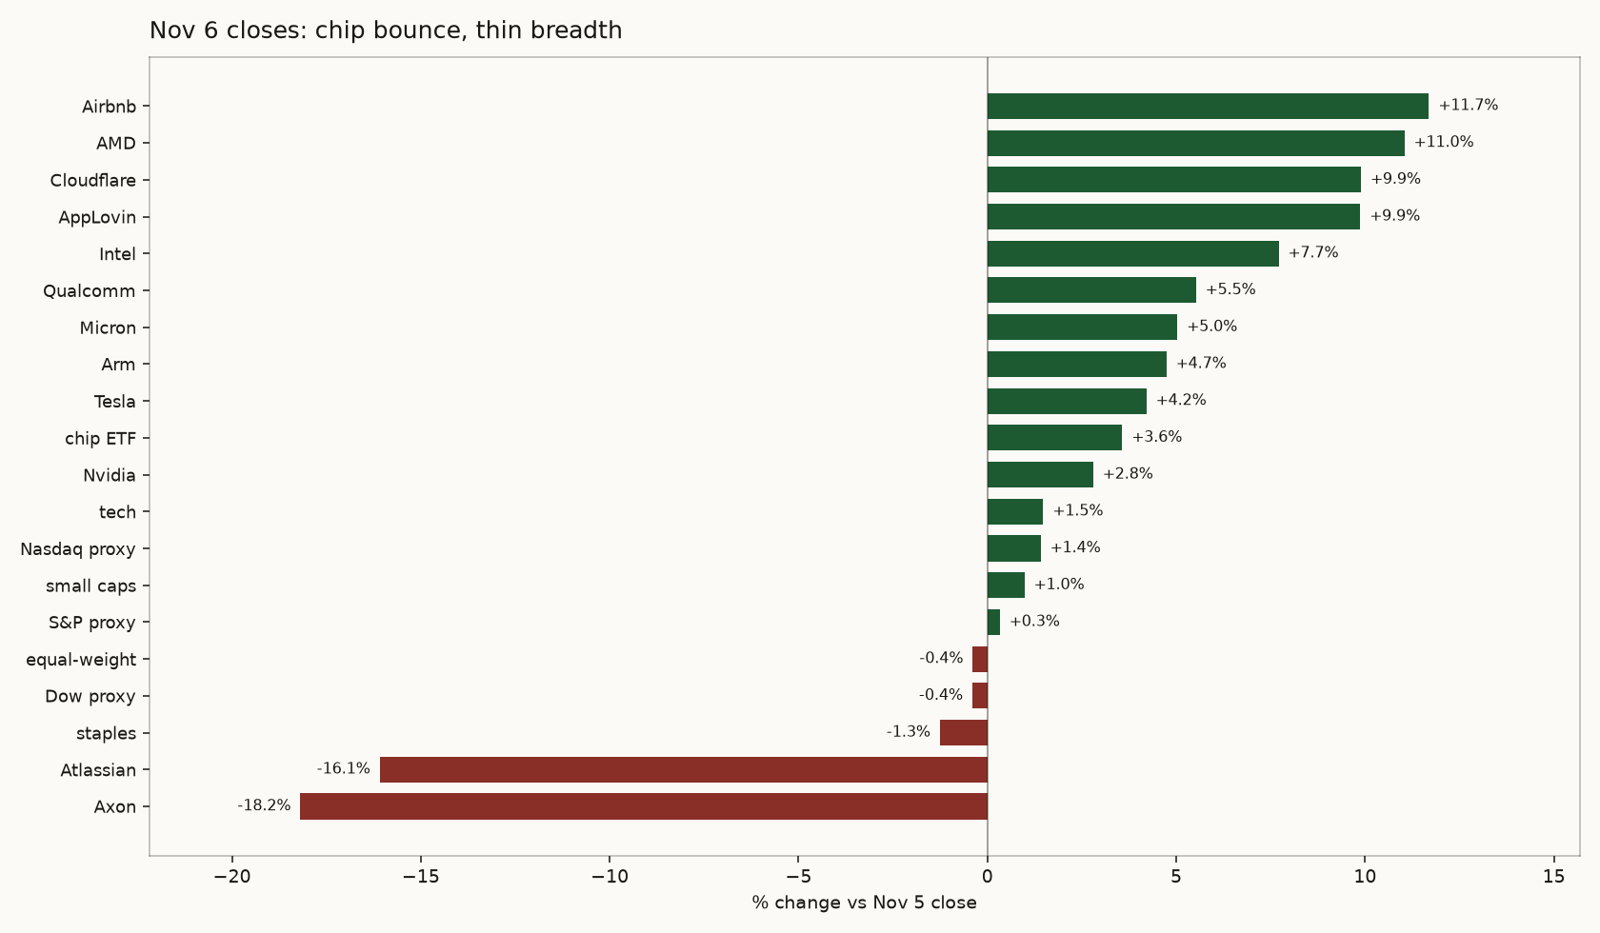
- The bounce was narrow: the chip ETF rose 3.57%, AMD 11.04%, Cloudflare 9.89% and Airbnb 11.69%, while the equal-weight S&P fell 0.39% and staples 1.26%; Atlassian fell 16.09% and Axon 18.19% after Thursday's reports.
- October payrolls printed 165,000 against 55,000 on the calendar (street near 70,000), unemployment fell to 4.1%, and Michigan sentiment rose to 51.0. After hours are quiet; Monday brings Chicago Fed President Austan Goolsbee at 10:00 AM ET, then KKR and Constellation Energy before the open.
Key numbers
Friday, November 6 turned Thursday's Bleeding session into a Choppy bounce that never broadened. Futures were already higher in chips before the open, then October payrolls printed 165,000 against a 55,000 forecast on the calendar and a street read near 70,000, with unemployment at 4.1% and wages up 0.4% month over month. The dollar and hike talk firmed, but buyers still chased the names that fell hardest yesterday. By the close the S&P proxy was up about 0.3%, the Nasdaq proxy about 1.4%, small caps about 1.0% and the Dow proxy down about 0.4%, with the vol proxy only about 1.2% lower.
Breadth told the real story. The equal-weight S&P fell about 0.4% while the index rose, a nearly 0.7-point gap the other way from Thursday, and staples were the worst sector group at about −1.3%. Tech led at about +1.5%. The chip ETF rose about 3.6%, AMD about 11.0%, Micron about 5.0%, Qualcomm about 5.5%, Arm about 4.7%, Nvidia about 2.8% and Intel about 7.7%. Cloudflare closed up about 9.9% and Airbnb about 11.7% after Thursday's beats, while Atlassian fell about 16.1% and Axon about 18.2%. AppLovin added about 9.9%. Long Treasuries were flat, crude about +0.1%, gold about −0.8% and Bitcoin about +0.4%.
The jobs print was hot end to end, street-reported: private payrolls 159,000, a two-month net revision of +84,000, and manufacturing payrolls 19,000. University of Michigan preliminary sentiment rose to 51.0 against about 47.2 to 48.0 on the calendar, with one-year inflation expectations easing to 4.3%. After the close, the calendar was thin (Hawaiian Electric and a micro-cap), so the tape stayed quiet into the weekend.
Research
Wires and posts say December Fed hike odds jumped after the payrolls beat, with some desks putting the chance near four in five. That is the other side of Thursday's AI-regulation scare: chips got a technical bounce, but a hotter labor market puts rate-cut hopes further out and keeps the average stock from confirming. Options volume hit a record on Thursday's washout, posts say, so today's rebound is still working through that positioning.
What X is saying
Posts say the chip rebound is a hangover bounce from Thursday's selloff rather than a clean breadth recovery, and that hot payrolls put a December hike back on the table. Some accounts call the Nasdaq futures rebound misleading while trend-following funds may still need to cut. Others note that the equal-weight S&P refused to join even as AMD and Airbnb ran double digits.
Insight
Today answered Thursday with a partial chip bounce and a hot jobs print, not with a market-wide repair. The Nasdaq proxy and the equal-weight S&P again traded more than a point apart, so the average-stock story cooled on the rebound. Monday's first catalyst is Chicago Fed President Austan Goolsbee at 10:00 AM ET; until then the board stays Choppy unless breadth catches the chip bid.
- HeatingThe AI spending boomThe chip ETF rose 3.57% and AMD 11.04% as buyers returned after Thursday's 11.57% chip washout, though the bounce recovered only part of the loss.
- CoolingThe average stock catching upThe equal-weight S&P fell 0.39% while the S&P proxy rose 0.33% and the Nasdaq proxy 1.41%, so megacaps and chips retook the lead on the rebound day.
- Played outOil's Middle East runCrude rose 0.13% to 148.41, still below the 150 line that ended the story, so the quiet session leaves it played out.
SOURCES ›
- Economic calendar 2026-11-06: October employment report 8:30 AM ET (forecast 55,000 on calendar / ~70,000 street, prior 29,000 revised to 60,000; actual 165,000 street-reported), unemployment rate (forecast 4.2%, prior 4.2%; actual 4.1%), average hourly earnings M/M (forecast 0.3%, prior 0.1% revised to 0.3%; actual 0.4%) and Y/Y (forecast ~2.9%, prior 3.0% revised to 3.2%; actual 3.1%), U. Michigan prelim 10:00 AM ET (forecast ~47.2–48.0, prior 46.3–48.0; actual 51.0), Fed governor Michelle Bowman 12:15 PM ET, consumer credit 3:00 PM ET; 2026-11-09: Chicago Fed President Austan Goolsbee 10:00 AM ET; 2026-11-10: October CPI 8:30 AM ET
- Earnings 2026-11-06 after the close: HE, TOMZ (thin); 2026-11-09 before the open include KKR, CEG, FERG, NRG (EPS est and implied moves on the calendar)
- Quotes as of 4:00 PM ET 2026-11-06 vs 2026-11-05 closes: SPY, QQQ, IWM, DIA, RSP, SMH, TLT, VXX, UUP, USO, GLD, XLK, XLF, XLE, XLY, XLP, XLI, XLV, XLU, XLRE, XLB, XLC, NVDA, AMD, MU, ARM, QCOM, INTC, AVGO, NET, ABNB, APP, TSLA, AAPL, MSFT, AMZN, META, GOOGL, TEAM, AXON, MNST
- After-hours quotes as of about 5:10 PM ET vs the 4:00 PM ET close: SPY, QQQ, SMH, NET, ABNB, AMD, MU, NVDA, INTC
- Bitcoin as of about 5:12 PM ET vs midnight ET
- Chart: the same closing quotes for Airbnb, AMD, Cloudflare, AppLovin, Intel, Qualcomm, Micron, Arm, Tesla, chip ETF, Nvidia, tech, Nasdaq proxy, small caps, S&P proxy, Dow proxy, equal-weight, staples, Atlassian and Axon
- 10-year Treasury yield street-reported +6.3 bp to 4.898% after the jobs print
- @FirstSquawk — “US NONFARM PAYROLLS (OCT) ACTUAL: 165K VS 29K PREVIOUS; EST 70K”
- @FirstSquawk — “US UNEMPLOYMENT RATE (OCT) ACTUAL: 4.1% VS 4.2% PREVIOUS; EST 4.2%”
- @FirstSquawk — “US AVERAGE HOURLY EARNINGS (MOM) (OCT) ACTUAL: 0.4% VS 0.1% PREVIOUS; EST 0.3%”
- @LiveSquawk — “US Change in Nonfarm Payrolls Oct: 165K (est 70K; prev 29K; prev R 60K). Unemployment Rate: 4.1% (est 4.2%; prev 4.2%). Avg Hourly Earnings (M/M): 0.4% (est 0.3%; prev 0.1%; prev R 0.3%). Avg Hourly Earnings (Y/Y): 3.1% (est 2.9%; prev 3.0%; prev R 3.2%)”
- @DeItaone — “US OCT. NONFARM PAYROLLS RISE 165,000 M/M; EST. +70K US OCT. UNEMPLOYMENT RATE 4.1%; EST. 4.2% US OCT. TWO-MONTH PAYROLL NET REVISION ADDS 84,000”
- @DeItaone — “US TREASURY YIELDS EXTEND RISE AFTER JOBS DATA; 10-YEAR YIELD LAST UP 6.3 BPS AT 4.898%”
- @LiveSquawk — “US Univ. Of Michigan Sentiment Nov P: 51.0 (est 48.0; prev 48.0). Current Conditions: 51.0 (est 47.0; prev 46.7). Expectations: 50.9 (est 49.0; prev 48.8). 1-Year Inflation: 4.3% (est 4.6%; prev 4.7%). 5-10 Year Inflation: 3.4% (est 3.5%; prev 3.5%)”
- @DeItaone — “US CHIP STOCKS SURGE AS AI SECTOR REBOUNDS FROM BRUTAL SELLOFF”
- @zerohedge — “Blue-nami Hangover: Chips Bounce, Breadth Doesn't As Hot Payrolls Put December Hike Back On The Table”
- @DeItaone — “UBS WARNS NASDAQ FUTURES REBOUND MAY BE MISLEADING”
- @DeItaone — “US JOBS SURGE. FED HIKE ODDS REBOUND.”
- @DeItaone — “US OPTIONS TRADING HITS ALL-TIME RECORD AMID MARKET ROUT”
Get tomorrow's brief before the open.
One feature a day, every day. Free. Unsubscribe anytime. Privacy