- The average stock catching up is heating again: the equal-weight S&P is down about 2.0% today against about 4.5% for the Nasdaq proxy, a day after its highest close in a year.
- Bull: it is up about 5.3% since Sep 30 while the Nasdaq proxy is down about 10.7%. Bear: small caps are down about 2.9% today, so the rest of the market is falling too, just less.
- Friday's 8:30 AM ET jobs report, forecast at 55,000, then Tuesday's inflation report test whether the lead holds once the market bounces.
Key numbers
The average stock catching up is the story that flipped twice this week, and today puts it to a hard test. As of about 11:40 AM ET the Nasdaq proxy is down about 4.5% and the chip ETF about 8.0% as chipmakers keep selling. The equal-weight S&P, which gives every company in the index the same weight, is down about 2.0%, beating the S&P proxy's −2.9% by about 0.9 points. The question is whether money is moving into the rest of the market, or just leaving it more slowly.
The bull case
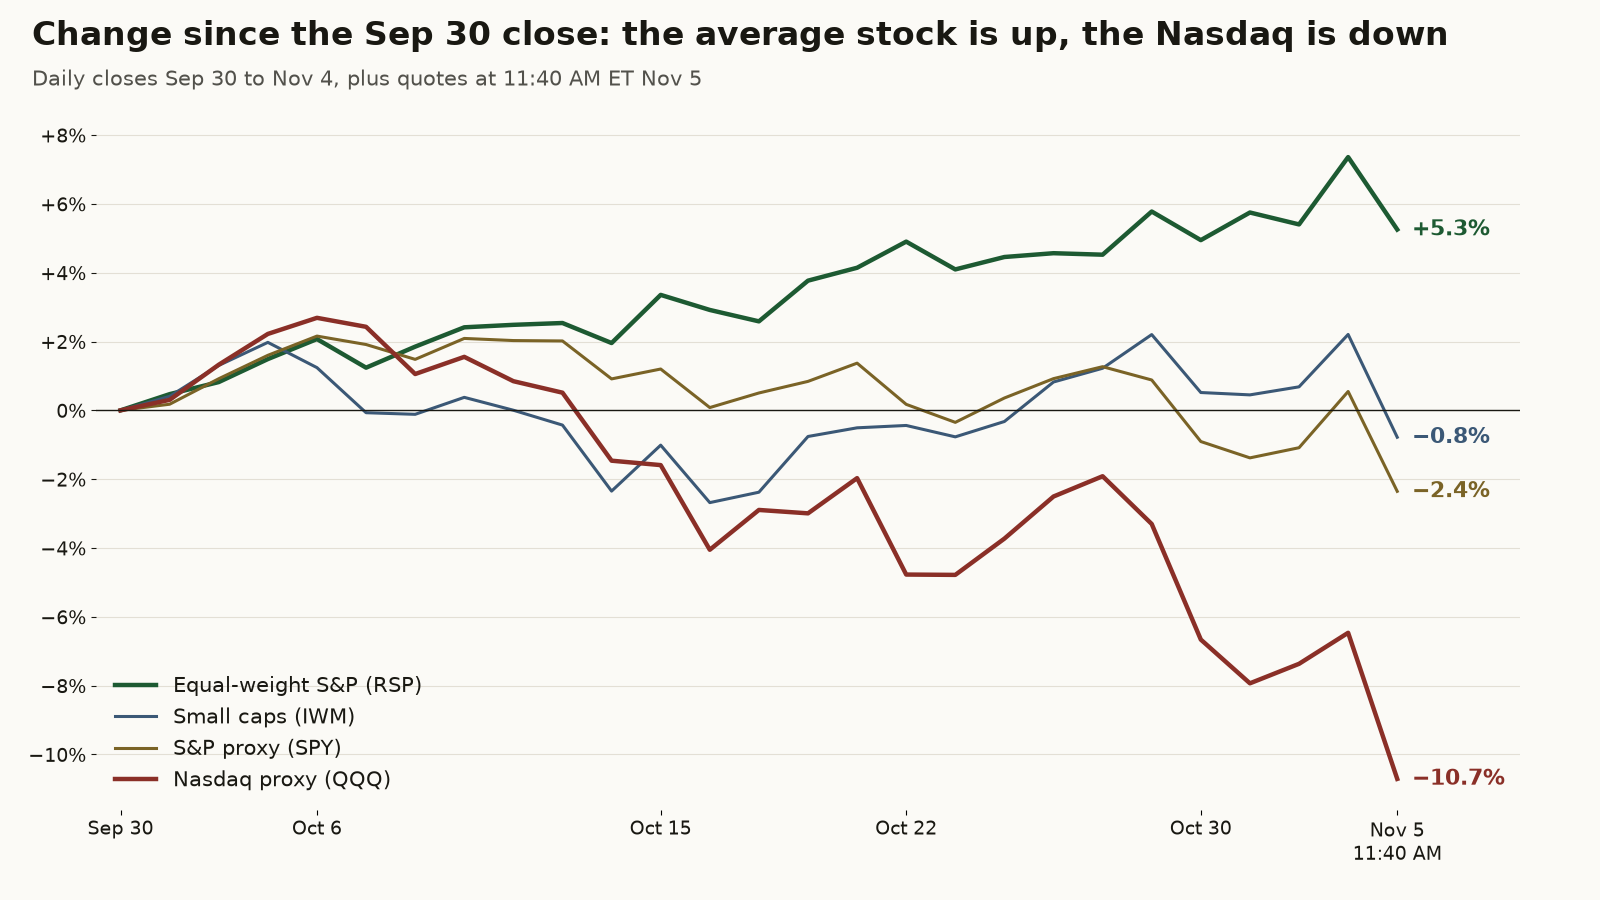
The gap has been building for five weeks, not one day. Since the Sep 30 close the equal-weight S&P is up about 5.3%, while the S&P proxy is down about 2.4% and the Nasdaq proxy about 10.7%. On Wednesday it closed at 223.33, its highest close in a year, while the Nasdaq proxy is still about 13% below its Oct 6 close. This week it is up about 0.3% even after today, against about −1.5% for the S&P proxy, and regional banks are up about 1.6%. The fear in options sits in big tech: through about 11:40 AM ET traders paid a net $156 million for Nasdaq proxy puts, while a net $19 million of small-cap puts were sold. Posts say equal weight "hit new highs ahead of price" as breadth widened on Wednesday.
The bear case
Falling less is not the same as leading. The equal-weight S&P is still down about 2.0% today, and small caps are down about 2.9%, as much as the S&P proxy, so the rest of the market is not acting as a shelter. Small caps are still about 0.8% below their Sep 30 close, which means most of the catch-up has come from big tech falling, not from smaller companies rising. Across all listed options, net call premium is about −$527 million through 11:40 AM ET, a broad pullback rather than a rotation trade, and the vol proxy is up about 17%. Posts caution that equal weight at highs with weak chips has historically meant "softer SPY/QQQ forwards, not an all-clear."
What would settle it
Three dates. Friday at 8:30 AM ET brings the October jobs report, with payrolls forecast at 55,000 after 29,000 and unemployment at 4.2%. A steady number helps the banks, factories and retailers that fill the equal-weight index, while a weak one tests whether small caps can hold. Tuesday, Nov 10 at 8:30 AM ET brings October consumer prices, after core prices rose 0.3% in September. Then Nvidia reports after the close on Nov 17, with options pricing a move of about 9.6%. The story ends if big tech retakes the lead for weeks while equal weight lags. Until then, the equal-weight S&P beating the S&P proxy on jobs day and through the inflation report keeps it alive.
Desk read
The evidence leans bull on the relative story, with moderate confidence. Five weeks of the equal-weight index beating the big-cap ones, a one-year high on Wednesday, and fear that sits in Nasdaq options rather than small-cap ones all point to a real broadening. The caution is that today the whole market is falling and small caps are falling with it, so the average stock is winning a relative race in a losing market. If it keeps its lead when the S&P proxy bounces, that is a handoff. If it only wins on down days, it is a softer landing. This is a read of the evidence, not a trade call.
- HeatingThe average stock catching upThe equal-weight S&P is down about 2.0% at 11:40 AM ET against the S&P proxy's 2.9%, a day after closing at 223.33, its highest close in a year.
- CoolingThe AI spending boomThe chip ETF is down about 8.0% and Nvidia about 6.4% at 11:40 AM ET, the selling that is doing most of the work for the equal-weight index.
SOURCES ›
- Economic calendar (pulled 11:41 AM ET Nov 5): Employment Report Nov 6 8:30 AM ET, October, forecast 55,000, prior 29,000; Unemployment Rate forecast 4.2%, prior 4.2%; Core CPI M/M Nov 10 8:30 AM ET, October, prior 0.3%
- Earnings calendar (pulled 11:41 AM ET Nov 5): NVDA 2026-11-17 postmarket, expected move about 9.6%
- Quotes at about 11:40 AM ET Nov 5 vs Nov 4 close: RSP 218.95 (−1.96%), SPY 744.69 (−2.89%), QQQ 660.54 (−4.54%), IWM 275.72 (−2.92%), SMH 464.06 (−7.97%), NVDA 187.25 (−6.44%), KRE 73.15 (−1.32%), VXX 19.97 (+17.06%)
- Daily closes Sep 30: RSP 208.02, SPY 762.63, QQQ 739.77, IWM 277.89; changes to 11:40 AM ET Nov 5: RSP +5.25%, SPY −2.35%, QQQ −10.71%, IWM −0.78%
- Daily closes Oct 30: RSP 218.31, SPY 755.72, QQQ 690.49, IWM 279.33, KRE 72.01; changes to 11:40 AM ET Nov 5: RSP +0.29%, SPY −1.46%, QQQ −4.34%, IWM −1.29%, KRE +1.58%
- Daily bars Nov 3, 2025 to Nov 4, 2026: RSP highest close 223.33 on Nov 4, 2026; QQQ highest close 759.66 on Oct 6, 2026 (QQQ −13.05% from it at 11:40 AM ET Nov 5)
- Options flow data (daily options volume, Nov 5 through about 11:40 AM ET): QQQ net put premium +$156.1M, net call premium −$55.3M; IWM net put premium −$19.2M, net call premium −$2.4M
- Options flow data (market-wide net premium, Nov 5 through 11:40 AM ET): net call premium −$527.3M, net put premium +$194.7M
- Mood Rattled per data/market/hero.json, 9:55 AM ET Nov 5 refresh
- @David_Tracey — “Equal weight (RSP) hit new highs ahead of price”
- @pineify — “Equal-weight at highs + weak semis historically = softer SPY/QQQ forwards, not an all-clear.”
Get tomorrow's brief before the open.
One feature a day, every day. Free. Unsubscribe anytime. Privacy