- Last week went Bleeding, Rattled, Choppy, Bleeding, Bleeding, and the AI spending boom won it in reverse: the chip ETF fell about 17.9%, the Nasdaq proxy about 10.3% and the S&P proxy about 8.4%, while long Treasuries rose about 2.6%.
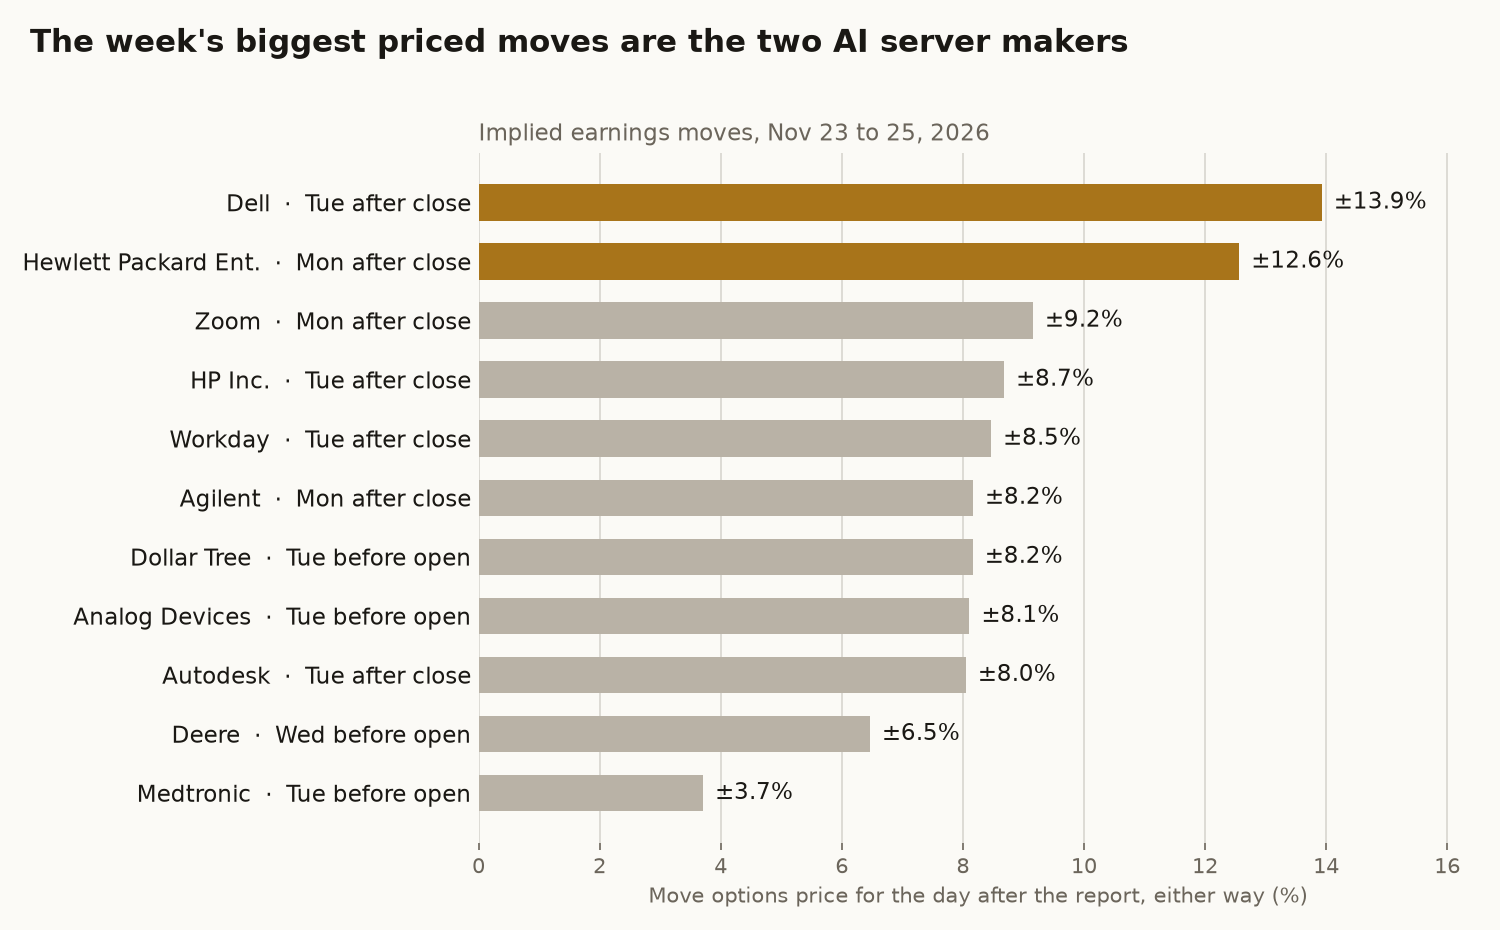
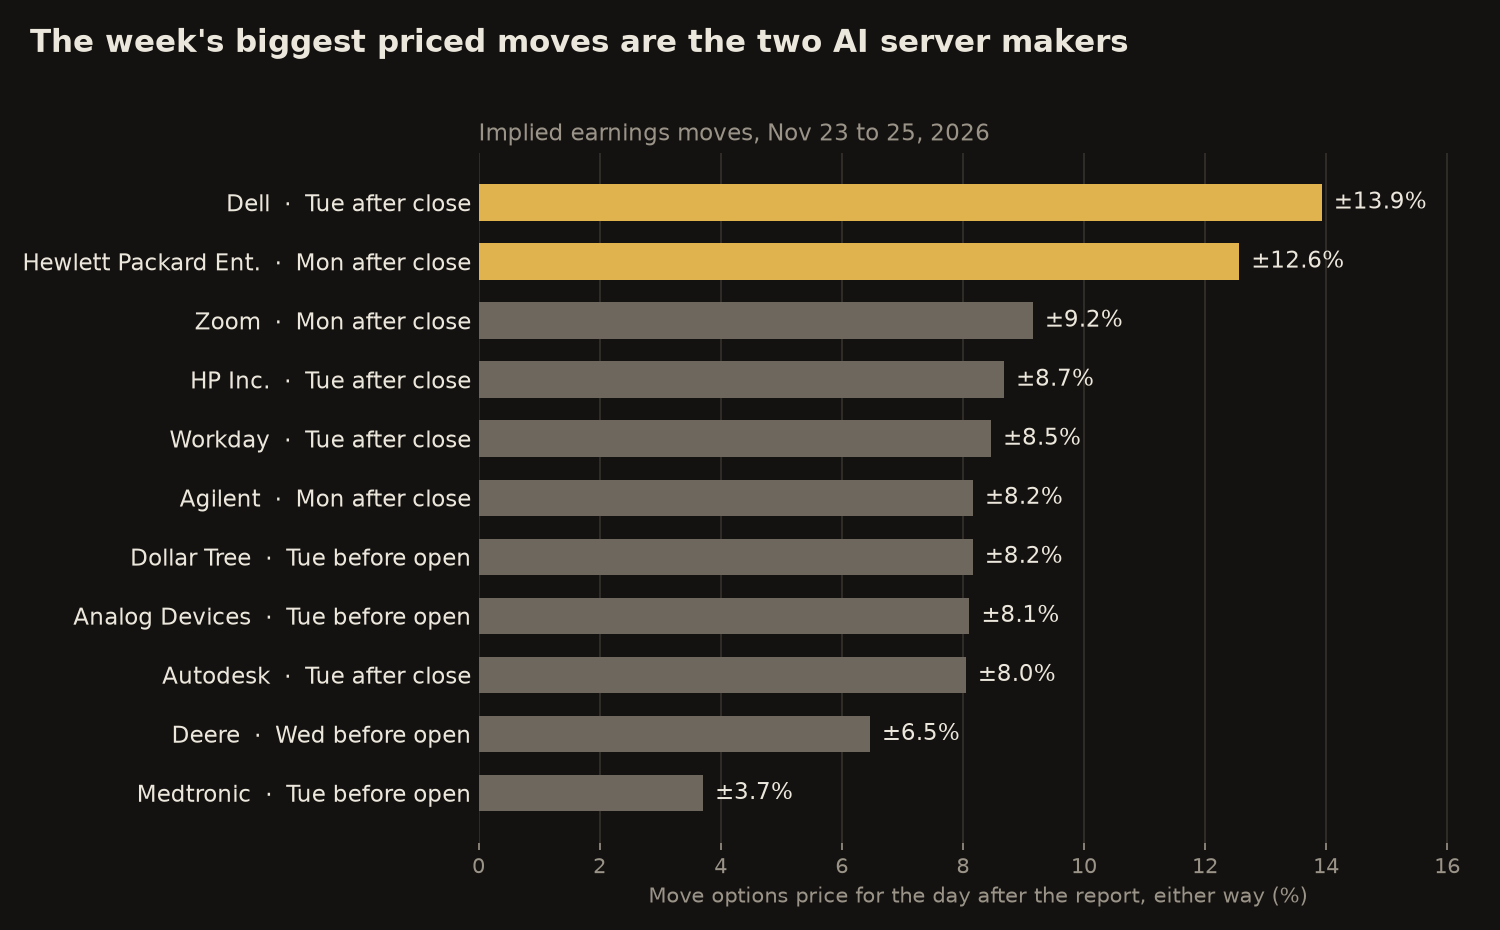
- The week's question is whether the selloff is only about AI or about the Fed too. Dell's report Tuesday after the close (options price about ±13.9%) tests AI demand, and Wednesday at 8:30 AM ET October's PCE inflation gauge (September +0.5%, core +0.3%) tests the hike that prediction markets price at about 90% for Dec 9.
- Monday has flash PMIs at 9:45 AM ET and New York Fed President Williams at 4:00 PM ET, with Hewlett Packard Enterprise (about ±12.6%), Agilent and Zoom after the close. Markets are closed Thursday for Thanksgiving and close at 1:00 PM ET Friday.
Key numbers
The week ahead
- 8:30 AM October PCE prices (prior +0.5%, core +0.3%)
- 8:30 AM Q3 GDP second estimate (prior 3.4%, forecast 3.4%)
- 8:30 AM Weekly jobless claims (prior 203K)
- 8:30 AM October durable goods (prior +1.8%, forecast +0.5%)
- 10:00 AM New home sales (prior 676K, forecast 648K)
- 2:00 PM Fed Beige Book
- DE BMO
- 8:30 AM Advance goods trade balance (prior −$135.1B)
- Early close: stocks 1:00 PM ET
Get the Desk's features and the market mood in your inbox. Free.
One feature a day, every day. Free. Unsubscribe anytime.
Last week was the week the AI trade broke. It closed Bleeding, Rattled, Choppy, Bleeding and Bleeding: the chip ETF fell about 17.9%, the Nasdaq proxy about 10.3% and the S&P proxy about 8.4%, while the vol proxy jumped about 45.6% and long Treasuries rose about 2.6%. Nvidia beat and raised, and still lost about 22.8%. So the short week ahead asks one thing: is this selloff only about AI, or is the Fed part of it too?
The week's question
Is the selloff only about AI, or about the Fed too? Wednesday at 8:30 AM ET answers it. October's PCE inflation gauge lands with the second estimate of third-quarter GDP (first estimate 3.4%), jobless claims (prior 203,000) and durable goods orders. September's PCE prices rose 0.5% on the month and 3.6% on the year, with the core up 0.3% and 3.1%. Prediction markets price about a 90% chance of a quarter-point hike on Dec 9, and Fed Governor Lisa Cook said Friday she dissented in October because she wanted another quarter point, calling inflation unacceptably high. A core reading at or under September's 0.3% would leave last week as an AI story, and a hotter one would make it a rates story too, a day before the market closes for Thanksgiving. The AI half gets tested first: Hewlett Packard Enterprise reports Monday after the close, priced for about 12.6% either way, and Dell Tuesday after the close at about 13.9%, or roughly $239 to $317 from Friday's $278.13. Dell's last three reports moved it about 15.8%, 32.8% and 21.9%. No CPI, jobs report, Fed decision or Mag 7 report falls this week, so the desk has no event note planned; the next big days are the jobs report Dec 4, the Fed Dec 9 and CPI Dec 10.
Stories in play
The AI spending boom (heating) runs through the server makers: Hewlett Packard Enterprise Monday, then Analog Devices before the open Tuesday (about ±8.1%), a chip read, and Dell, HP Inc. and Workday after the close. Hike bets weigh on long bonds (steady) meets Wednesday's data with long Treasuries at 81.43, just under the 82 line the story watches, and the Beige Book follows at 2:00 PM ET. Can the average stock catch up? (steady) gets the holiday shopper: Best Buy, Dollar Tree and Burlington report Tuesday before the open, after the equal-weight S&P fell about 6.1% last week against about 8.4% for the S&P proxy.
What X is saying
Posts say the weekend's mood is gloom about AI despite Nvidia's record sales. Accounts report that server makers including Dell and Hewlett Packard Enterprise are raising prices on Nvidia-powered AI servers by as much as 45%, months after contracts were signed; that is one newspaper's report, not a company statement, and it lands days before both report. Posts also say investor Michael Burry sold half of his Nvidia put position on Friday, which traders read as profit-taking rather than a change of view. Anthropic closed its first two sessions at 88.44, about 6.6% above its $83 offer, and weekend posts argue over whether the deal was priced right.
Desk stance for Monday
The desk expects Monday to open Rattled. Four of last week's five sessions closed Rattled or Bleeding and the vol proxy ended at 27.27, but the tape firmed after Friday's bell, with the S&P proxy at 697.49 near 8 PM ET, about 0.9% over its 690.91 close, and Nvidia at 130.01, about 3.4% higher. Monday's only scheduled data is the 9:45 AM ET PMIs, so the open trades on chips. A bounce that holds with the vol proxy easing would cool the tone to Choppy; the chip ETF slipping back under Friday's 399.77 close would keep it Bleeding into Hewlett Packard Enterprise's report.
- HeatingThe AI spending boomThe chip ETF fell about 17.9% last week; Hewlett Packard Enterprise Monday (about ±12.6%) and Dell Tuesday (about ±13.9%) are the week's AI demand tests.
- SteadyHike bets weigh on long bondsLong Treasuries rose about 2.6% to 81.43, still under 82, with prediction markets near 90% on a Dec 9 hike; Wednesday's PCE data is the test.
- SteadyCan the average stock catch up?The equal-weight S&P fell about 6.1% against about 8.4% for the S&P proxy last week; Best Buy, Dollar Tree and Burlington report Tuesday before the open.
SOURCES ›
- Economic calendar feed pulled 6:41 AM ET 2026-11-22 returned no rows for the week, so releases come from agency schedules and published week-ahead calendars. BEA release schedule (bea.gov/news/schedule), read 6:50 AM ET: Wed Nov 25 8:30 AM ET GDP (Second Estimate) Q3 2026 and Personal Income and Outlays, October 2026. Priors from the agencies: BEA Oct 29 releases (Q3 GDP advance +3.4% annual rate; September PCE prices +0.5% m/m and +3.6% y/y, core +0.3% m/m and +3.1% y/y); Census advance durable goods report (September new orders +1.8%).
- Other times, priors and forecasts from a bank economics desk's week-ahead table dated Nov 20 and a news magazine's weekly calendar dated Nov 20, which agree on dates and times: Mon 11/23 9:45 AM ET flash manufacturing PMI (forecast 54.5, prior 54.9) and services PMI (55.7, 56.1), 4:00 PM ET New York Fed President Williams keynote; Tue 11/24 10:00 AM ET consumer confidence (92.1, 91.7); Wed 11/25 8:30 AM ET GDP (forecast 3.4%), initial jobless claims week ended Nov 21 (prior 203K), durable goods (forecast +0.5%), 10:00 AM ET new home sales (648K, 676K), 2:00 PM ET Fed Beige Book; Fri 11/27 8:30 AM ET advance goods trade balance (prior −$135.1B).
- NYSE holidays and trading hours (nyse.com/markets/hours-calendars): closed Thursday Nov 26 2026 for Thanksgiving; early close 1:00 PM ET Friday Nov 27 2026 (from the desk's Spaghetti Saturday 2026-11-21 sources).
- Earnings calendar, pulled 6:41 AM ET 2026-11-22, expected moves: Mon 11/23 after the close HPE 12.56%, ZM 9.15%, A 8.16%, J 7.75%; Tue 11/24 before the open ADI 8.11%, DLTR 8.16%, BBY 7.95%, BURL 10.00%, MDT 3.71%; after the close DELL 13.93%, HPQ 8.68%, WDAY 8.46%, ADSK 8.05%, NTNX 13.34%; Wed 11/25 before the open DE 6.46%. Dates and sessions cross-checked against a broker earnings calendar (all company-verified, no disagreements).
- Dell next-day moves after its last three reports from the earnings calendar history: 2026-09-01 +15.8%, 2026-05-28 +32.8%, 2026-02-26 +21.9%.
- Next CPI Dec 10, jobs Dec 4 and FOMC decision Dec 9 from data/econ schedules.
- Closing quotes 4:00 PM ET 2026-11-20 vs 2026-11-13 closes: SPY 690.91 vs 754.37 (−8.41%), QQQ 610.04 vs 679.89 (−10.27%), RSP 207.56 vs 221.16 (−6.15%), SMH 399.77 vs 486.75 (−17.87%), TLT 81.43 vs 79.38 (+2.58%), VXX 27.27 vs 18.73 (+45.59%); NVDA −22.76% to 125.79; DELL 278.13, HPE 40.925 (40.93). Week closes from the desk's Vibe Check Friday 2026-11-20.
- After-hours quotes about 7:59 PM ET 2026-11-20: SPY 697.49 (+0.95% vs 690.91), NVDA 130.01 (+3.35% vs 125.79).
- Dell implied range: 278.13 × (1 ± 0.1393) is about $239.40 to $316.86.
- Prediction-market prices for the December 2026 Fed decision, read 6:43 AM ET 2026-11-22: +25 bp 0.895, no change 0.0655, +50 bp 0.0215, −25 bp 0.0055.
- Fed Governor Lisa D. Cook, The U.S. Economy in Global Context, Nov 20 2026 (federalreserve.gov/newsevents/speech/cook20261120a.htm): dissented in October, preferring to raise the target range another 1/4 percentage point; called inflation unacceptably high.
- Anthropic (ANT) closes 2026-11-19 97.17 and 2026-11-20 88.44 vs $83.00 offer (+6.55%), from quotes and the desk's event note event-ant-2026-11-19.
- Closing moods 2026-11-16 to 2026-11-20 from data/market/day-moods.json: bleeding, rattled, choppy, bleeding, bleeding; current mood from data/market/hero.json (bleeding). Narrative heat from data/narratives (ai-spending, long-yields, average-stock).
- Chart: the implied moves listed in the earnings calendar entry above.
- @FT — “Tech suppliers including Dell, HPE, Lenovo and Supermicro are raising prices for Nvidia-powered AI servers by as much as 45 per cent, months after contracts have been signed, as soaring demand for computing power drives up costs.”
- @WatcherGuru — “JUST IN: "Big Short" investor Michael Burry says he sold half of his Nvidia $NVDA short position.”
- @burrytracker — “Just In: Michael Burry sold 50% of his $NVDA puts”
- @FT — “Did Anthropic and its bankers get a key call wrong after IPO?”
Get tomorrow's feature in your inbox.
One feature a day, every day. Free. Unsubscribe anytime. Privacy